Positive year-end update, ahead of expectations
A positive year-end update from Hercules Site Services plc (LON:HERC) confirms a strong conclusion to FY23, ahead of expectations. It has been another year of excellent organic revenue growth (+60% at Group level), with progress in all three divisions. This continues an impressive track record (average revenue growth over past three years >50%) and Hercules enters FY24 with momentum.
Strong trading update prompts forecast upgrades
Hercules expects both its revenue and adjusted EBITDA for FY23 to be ahead of market expectations. Revenue is expected to be > £80m, representing an upgrade of at least 8% to previous expectations. We assume a similar uplift to our EBITDA forecast (+8% to £3.7m) with the headline changes set out on page 2 of this note.
Divisional highlights – organic growth across the board
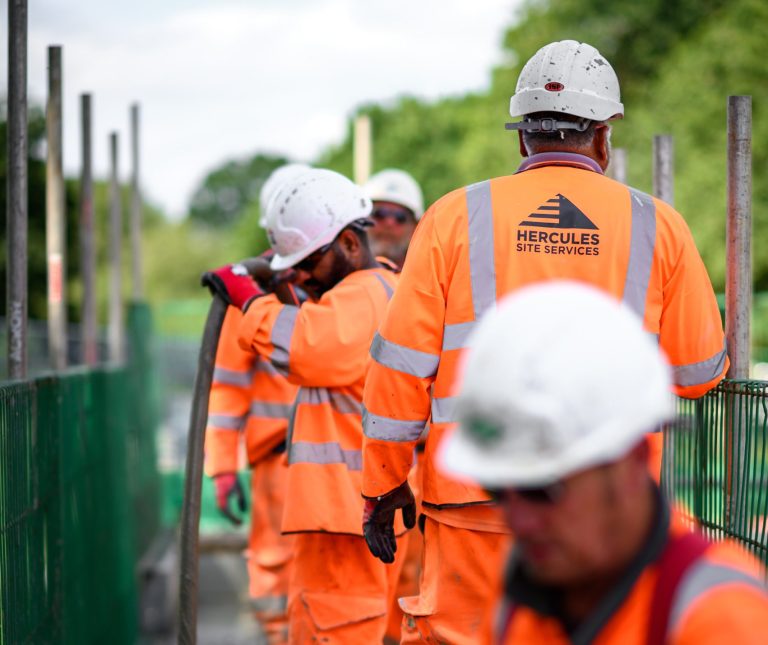
All three divisions have delivered organic revenue growth. The overall performance has again been driven by the core Labour Supply business, which benefited from the ramp-up of the multi-year HS2 Phase 1 contract (London to Birmingham). Activity on this contract continued to increase as the year progressed and there are now some 430 Hercules operatives on site. Post year-end, Hercules announced a new five year “live tracks” contract supplying labour to Balfour Beatty Rail Limited. In Civils, the Group is benefiting from increasing investment in the water sector, as illustrated by the £3.1m of contract awards announced on 20th September. Meanwhile, the Suction Excavator business continues to see solid utilisation rates, having expanded by 14 vehicles over the period to create one of the largest fleets in the country.
Positive outlook for sustained earnings growth
As we wrote in our initiation note, we expect growth to be supported by a favourable outlook for infrastructure spending, a structural undersupply of skilled labour and Hercules’ recent organic investment in technology and fleet expansion. Today’s update confirms continuing momentum.
In our view, the Group’s strong growth trajectory and forecast free cash flow (double digit FCF yield) suggest significant value in the shares. Our Fair Value per share of 60p represents a 7.5% FCY yield on prudently positioned FY25 forecasts.
Read the full Hercules Site Services plc note from Equity Development here: