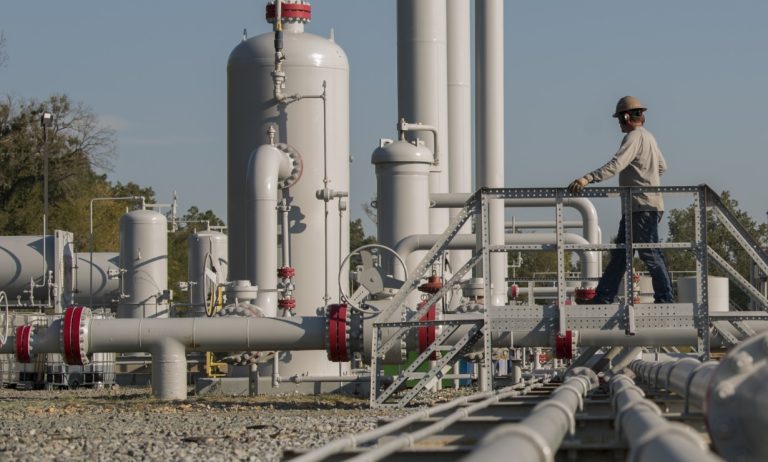
Diversified Energy Company (LON:DEC) has taken a bold step towards expansion with the acquisition of Maverick Natural Resources, a move that significantly enhances its scale, revenue diversification, and growth potential. The deal, valued at US$1.275 billion, is expected to deliver substantial synergies, reinforcing DEC’s position as a major force in the US energy sector.
A Game-Changing Acquisition
The Maverick acquisition marks DEC’s most significant consolidation to date, increasing its production by 41% to ~200 kboepd across five basins. The move is also set to nearly double its revenue, taking it to US$1.8 billion (+96%), while EBITDA will see a 68% uplift to US$935 million.
Tim Hurst-Brown, analyst at Tennyson Securities, emphasised the transformational nature of the deal, stating:
“The acquisition of Maverick Natural Resources represents a step-change for DEC and by far its largest consolidation move to date.”
This strategic expansion is expected to generate over US$50 million in immediate cost synergies, reducing operating expenses and unlocking further value.
A Stronger, More Balanced Business Model
One of the most compelling aspects of the deal is how well Maverick’s portfolio aligns with DEC’s existing business. The acquired assets are long life and low decline (~10% natural depletion), ensuring sustained production with relatively low capital intensity.
Additionally, the increased exposure to liquid assets (55% of Maverick’s production mix) enhances cash flow resilience. Post-acquisition, more than a quarter of DEC’s production will be linked to oil prices, reducing its reliance on the more volatile natural gas market and increasing unit cash margins by 26% to US$2.02/mcfe.
Financial Strength and Growth Optionality
The deal is fully funded through a mix of vendor equity (21.1 million DEC shares worth ~US$343 million), cash (US$207 million), and inherited debt (US$700 million). DEC has secured US$900 million in new credit commitments, ensuring a smooth financial transition.
Crucially, the transaction is leverage accretive, lowering the company’s net debt/EBITDA ratio from 2.9x to 2.7x, bringing it closer to DEC’s target of 2.5x. The acquisition also reinforces DEC’s ability to maintain its US$0.29 per share quarterly dividend, equating to an enlarged annual payout of US$84 million (+41%).
Expanding Market Influence
This deal not only strengthens DEC’s operational profile but also enhances its market positioning. Post-acquisition, the company’s market capitalisation will increase by ~50%, and its enterprise value will reach US$3.7 billion.
Furthermore, with Maverick’s major shareholder, EIG Partners, taking a 20% stake in DEC and securing two board seats, the company is now positioned for a potential primary listing on the NYSE later in 2025. This shift is expected to improve liquidity, attract more US investors, and potentially re-rate the stock towards US energy sector valuations.
Final Thoughts
Diversified Energy’s acquisition of Maverick Natural Resources is a transformative move that strengthens its financials, enhances its operational efficiency, and broadens its market reach. As Tennyson Securities reiterates its BUY recommendation with a target price of £20 per share—a 50% upside from current levels—it’s clear that DEC is on an impressive growth trajectory.
With stronger cash flows, reduced leverage, and an expanded asset base, the company is well-positioned to capitalise on further opportunities in the US energy market. Investors seeking exposure to a high-yielding, cash-generative energy play should keep a close eye on Diversified Energy in 2025.