Sintana Energy (LON:SEI) has been initiated with a Buy recommendation and a 62p target price in the latest research note from Cavendish, authored by Research Analyst James McCormack. The note, titled Walking amongst giants, sets out a detailed valuation case built around a world class offshore portfolio and a catalyst rich exploration programme .
At the time of publication, the shares were trading at 24.0p, implying 158% upside to Cavendish’s 62p target price . The broker believes the company is trading at a material discount to its risked Net Asset Value and to its peer group.
A World Class Portfolio in Emerging Basins
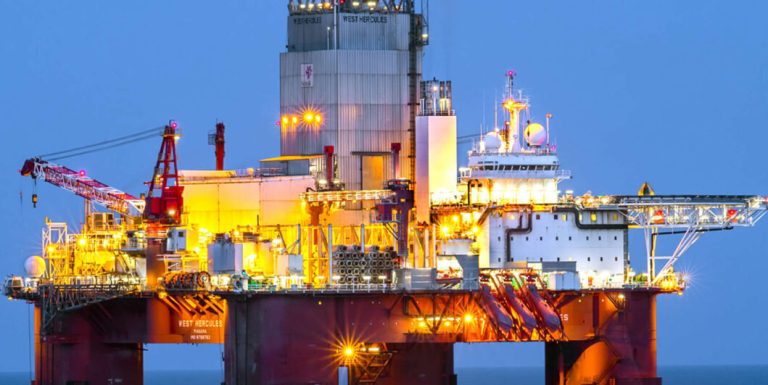
Sintana Energy is described in the research note as “a unique and exciting E&P company, with a portfolio that includes an interest in one of the world’s largest oil discoveries offshore Namibia and partnering in multiple other high impact licences with oil and gas Supermajors and NOCs” .
The centrepiece of the portfolio is a 4.9% effective interest in the giant Mopane discovery offshore Namibia, estimated at over 10bn barrels of oil in place. Importantly, Sintana’s capital commitments are largely carried by partners including TotalEnergies and Galp, limiting financial exposure while retaining upside.
Cavendish calculates a risked core NAV of US$309m, equivalent to 42.7p per share, based predominantly on Mopane. Including selected exploration assets, total risked NAV rises to US$450m, or 62.1p per share .
Extensive Near Term Catalysts
One of the key attractions highlighted in the research is the near term activity profile. Sintana has exposure to multiple wells across Namibia and Uruguay over the coming 12 to 24 months, both directly and indirectly.
The note states that “Sintana is set for a busy 2026, with direct exposure of up to four wells in the next 12 months and indirect exposure to a similar number of wells to be drilled nearby by third parties which could provide a de-risking of Sintana’s opportunities” .
Data rooms are open on several licences, with partnering discussions ongoing. In addition, seismic acquisition and subsurface modelling programmes are expected to refine prospectivity and support farm down processes.
Strong Alignment and Capital Efficiency
Management alignment is another central pillar of the investment case. Directors and senior management collectively hold over 15% of the issued share capital, ensuring alignment with shareholders .
The company has raised only around US$10m of new equity since listing, yet through partner carries it has exposure to over US$1bn of work programmes across its acreage . This capital efficient model allows participation in high impact exploration while limiting balance sheet strain.
Financially, Sintana remains pre revenue, with cash resources estimated in the region of US$7m and annual G&A and joint venture costs expected to remain under US$4m per annum according to Cavendish forecasts .
Valuation Case
Cavendish concludes that “We believe Sintana is substantially undervalued based on fundamental DCF valuation and peer analysis. Our target price is set at risked total NAV of 62p” .
With exposure to one of the largest recent deepwater discoveries globally, alongside multiple frontier and emerging basin opportunities, the broker believes the shares do not reflect the scale of potential embedded in the portfolio.
Final Thoughts
The latest research note from Cavendish positions Sintana Energy as a differentiated Atlantic Margin explorer with carried exposure to a giant discovery and a steady stream of exploration catalysts. While exploration risk remains inherent, the combination of partner funding, management alignment and valuation discount underpins the Buy recommendation and 62p target price. As 2026 unfolds with multiple operational milestones, the coming months could prove pivotal for the company.