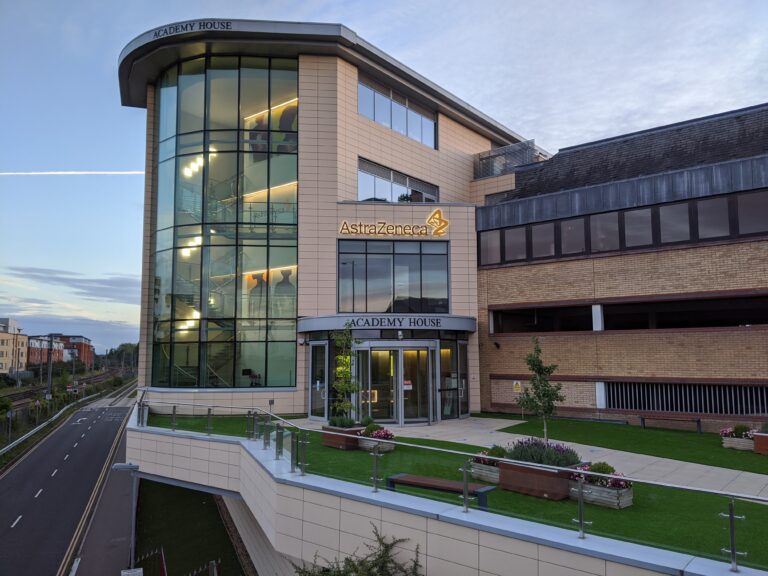
AstraZeneca PLC (NASDAQ: AZN), a leading player in the global healthcare sector, is currently capturing investor attention with its impressive market cap of $292.78 billion and a robust revenue growth rate of 12%. As a major force in the drug manufacturing industry, AstraZeneca’s strategic collaborations and expansive product portfolio make it a compelling consideration for investors seeking exposure to the healthcare sector.
Currently trading at $94.427, AstraZeneca’s stock price is nearing the upper bound of its 52-week range of $64.87 to $96.34. Despite its proximity to the peak, the average target price of $98.96 suggested by analysts indicates a potential upside of 4.8%. This modest growth forecast is supported by the company’s forward P/E ratio of 18.37, which aligns with industry expectations for a company of its caliber.
The British pharmaceutical giant’s commitment to innovation is evident in its diverse array of products, which cater to oncology, cardiovascular, renal and metabolism, respiratory and immunology, and rare diseases. Notably, AstraZeneca’s strategic collaborations, such as those with Tempus and IonQ, Inc., underscore its drive to leverage cutting-edge technologies in drug discovery and development. These alliances are likely to bolster its pipeline and, in turn, its financial performance.
AstraZeneca’s financial health is underscored by its strong free cash flow of approximately $9.98 billion, which provides a solid foundation for ongoing R&D investments and strategic acquisitions. Moreover, the company’s return on equity (ROE) stands at an impressive 21.67%, reflecting efficient management and robust profitability.
For income-focused investors, AstraZeneca offers a dividend yield of 1.66% with a payout ratio of 51.99%. This indicates a balanced approach to rewarding shareholders while retaining sufficient earnings for future growth initiatives.
From a technical standpoint, AstraZeneca’s stock exhibits strong momentum. The current Relative Strength Index (RSI) of 71.40 suggests that the stock is in overbought territory, which may signal a short-term pullback. However, the stock’s position comfortably above both the 50-day moving average of $90.99 and the 200-day moving average of $78.81 indicates a strong upward trend.
Analyst sentiment towards AstraZeneca remains predominantly positive, with 10 buy ratings and a single hold rating, and no sell ratings. This optimistic outlook is supported by the company’s strategic initiatives and robust financial performance, which continue to drive investor confidence.
AstraZeneca’s strategic focus on expanding its product portfolio and enhancing its innovation capabilities positions it well for sustained growth. As the healthcare landscape continues to evolve, AstraZeneca’s proactive approach in forming strategic alliances and advancing its research capabilities could unlock further value for shareholders. Investors should keep a close watch on upcoming earnings reports and partnership announcements that may provide further insight into the company’s growth trajectory.