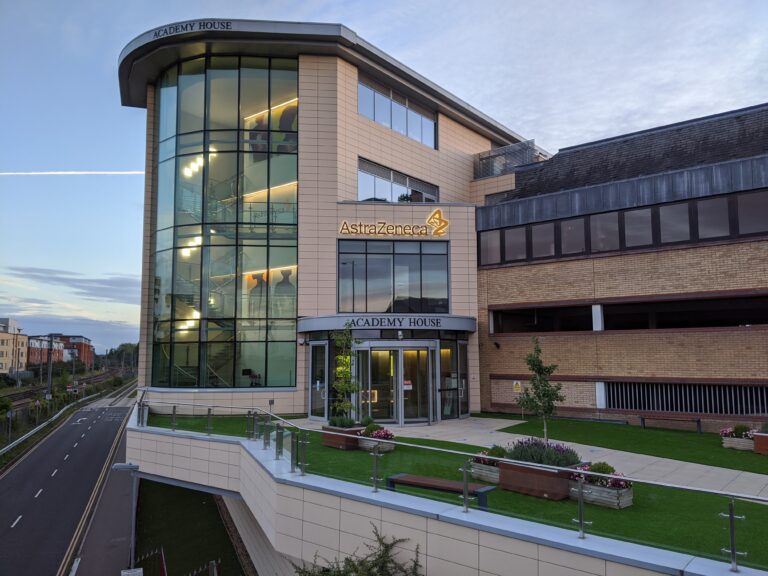
AstraZeneca PLC (AZN), a titan in the healthcare sector, is renowned for its robust portfolio of prescription medicines that cater to a broad spectrum of medical needs. From oncology to respiratory and immunology, AstraZeneca’s commitment to innovation is evident in its diverse product lineup, which includes well-known names like Imfinzi, Lynparza, and Farxiga. As investors explore opportunities in the healthcare industry, AstraZeneca’s strategic partnerships and strong market presence present a compelling case for consideration.
A glance at AstraZeneca’s financial metrics reveals a company with a substantial market capitalization of $245.46 billion. Currently trading at $79.17, the stock has exhibited a 52-week price range between $63.20 and $87.62, indicating a level of volatility that investors should be mindful of. However, the current price remains above both the 50-day and 200-day moving averages, suggesting a positive momentum.
The forward P/E ratio of 15.48 offers insight into the company’s valuation, positioning it as a relatively attractive investment, especially when coupled with a notable revenue growth of 11.70%. The company’s impressive return on equity of 19.67% underscores its ability to generate profit from shareholders’ investments, a metric that often signals strong financial health and efficiency.
While AstraZeneca’s earnings per share (EPS) stands at 2.65, the absence of a trailing P/E ratio and other valuation metrics like the PEG ratio or price/book may leave some investors seeking additional context. Nonetheless, the company’s free cash flow of approximately $8.97 billion provides a solid foundation for continued growth and reinvestment in research and development, a critical component in the pharmaceutical industry.
AstraZeneca’s dividend yield of 1.98% and a payout ratio of 58.38% demonstrate a balanced approach, rewarding shareholders while retaining sufficient capital for strategic initiatives. This is further supported by the analyst ratings, with 9 buy recommendations and only 2 hold ratings, and no sell recommendations, reflecting overall confidence among analysts in AstraZeneca’s potential.
The company’s average target price of $86.61 suggests a potential upside of 9.40%, a figure that individual investors may find particularly enticing. Coupled with a favorable RSI of 30.41, which indicates that the stock might be nearing oversold territory, AstraZeneca could present a timely buying opportunity.
AstraZeneca’s strategic collaborations, such as those with Tempus and IonQ, Inc., highlight its commitment to advancing medical research and leveraging cutting-edge technology. These partnerships are not only aimed at enhancing the company’s existing product offerings but also at exploring new therapeutic areas, particularly in oncology and computational chemistry.
For investors, AstraZeneca represents a blend of stability and growth potential. Its expansive product portfolio, strategic partnerships, and promising financial performance provide a solid framework for those looking to invest in a company at the forefront of medical innovation. As AstraZeneca continues to navigate the complexities of the healthcare landscape, it remains a key player poised for future success.