The latest research note from Longspur Research highlights fresh momentum at Drax Group (LON:DRX), following the signing of a new tolling agreement that is expected to add meaningful value to the business. Longspur has increased its central case valuation to 1093p from 1082p, reflecting the benefits of the deal and the broader opportunity it represents .
Research Analyst Adam Forsyth points to the strategic importance of the agreement, writing, “The tolling agreement signed with Fidra Energy recently adds value to Drax and our central case valuation rises to 1093p from 1082p. We also see potential beyond this with the ability to find additional similar deals and to use the recently acquired Flexitricity to add further value.”
Unlocking Value in Battery Storage
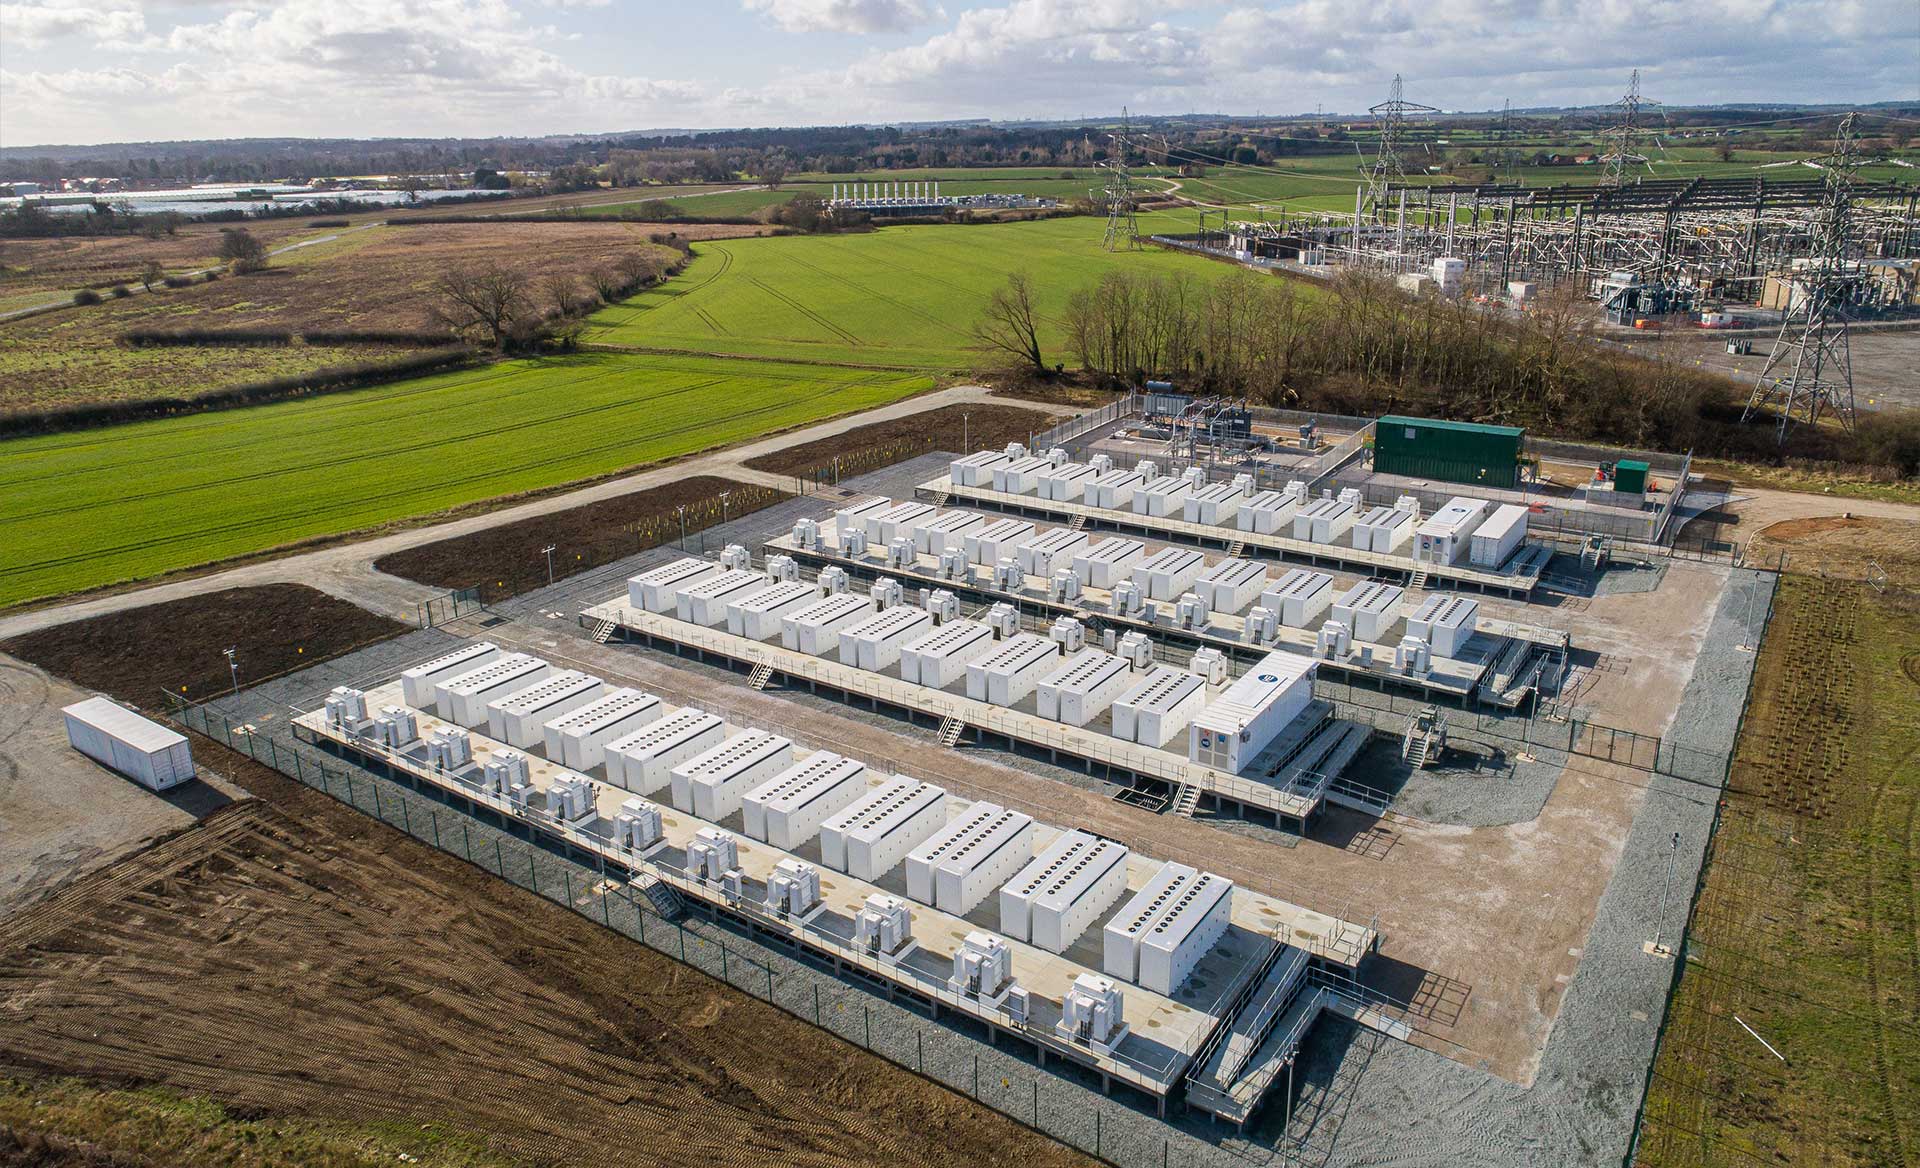
The agreement covers 250MW of battery capacity and is rooted in what Longspur describes as a gap in the storage market. While batteries are naturally suited to trading strategies, allowing operators to buy electricity when prices are low and sell when high, many developers are seeking long term tolling agreements to secure infrastructure style financing.
Forsyth explains, “Batteries are natural trading assets. They allow electricity traders to buy low and sell high.”
For Drax, this creates an opportunity. With a strong balance sheet and established trading and optimisation capabilities, enhanced further by the acquisition of Flexitricity, the group can access trading margins without significant upfront capital outlay. Longspur estimates that the West Burton deal could generate around £30m of EBITDA, reduced to £10m after tolling fees, but with no capital investment required .
The model is seen as scalable. With 83GW of battery energy storage system capacity issued Gate 2 grid connection offers, and 33GW expected to connect before 2030, there is a substantial pipeline of potential projects .
Forecast Changes and Valuation
Longspur has adjusted its forecasts to reflect the contribution of the West Burton deal from mid FY28. EBITDA in FY28 is now expected to reach £638m, up from £629m previously, and FY29 EBITDA is forecast at £713m, compared with £687m before .
Using a weighted average cost of capital of 8.8 percent, Longspur arrives at a valuation of 1093p. In a lower case scenario, assuming carbon capture does not proceed and the pellets business stalls, the valuation would be 942p. In a higher case, with carbon capture and storage progressing and expansion at Cruachan, the valuation could reach 1237p .
Financial Highlights
Longspur’s forecasts underline Drax’s resilience and cash generation, even as pricing normalises.
Key financial highlights:
- FY24 revenue of £6,163m, with EBITDA of £1,053m
- FY25 EBITDA forecast at £905m
- FY28 EBITDA forecast at £637m
- Net debt forecast to reduce to £848m by FY28
- Dividend per share expected to rise from 26.0p in FY24 to 38.2p by FY28
The research also notes that dividend payments remain covered throughout the forecast period .
Strategic Positioning in a Changing Market
Drax owns over 6GW of grid connected capacity in Great Britain and operates across biomass generation, hydro and pumped storage, flexible gas and pellet production . The group’s exposure to flexibility markets, low carbon spinning reserve and potential carbon capture and storage developments are identified as supportive factors.
At the same time, Longspur acknowledges risks including exposure to policy changes and the evolving economics of BECCS technology .
Final Thoughts:
This latest research note from Longspur Research presents a constructive view on Drax Group. The tolling agreement not only enhances near term value but also opens up a repeatable, capital light growth model in battery storage. With improving forecasts and a higher valuation target, Drax appears well positioned to benefit from growing demand for flexibility and low carbon generation in the UK power market.