Victorian Plumbing Group plc (LON:VIC) was the topic of conversation when DirectorsTalk interviewed Gervais Williams, Co-Fund Manager of Premier Miton UK Multi Cap Income Fund.
DirectorsTalk asked: Victorian Plumbing delivered double-digit revenue growth for the first half with record order volumes and particularly strong growth in tiles and flooring. What is driving that progress and what makes the company an attractive investment from here?
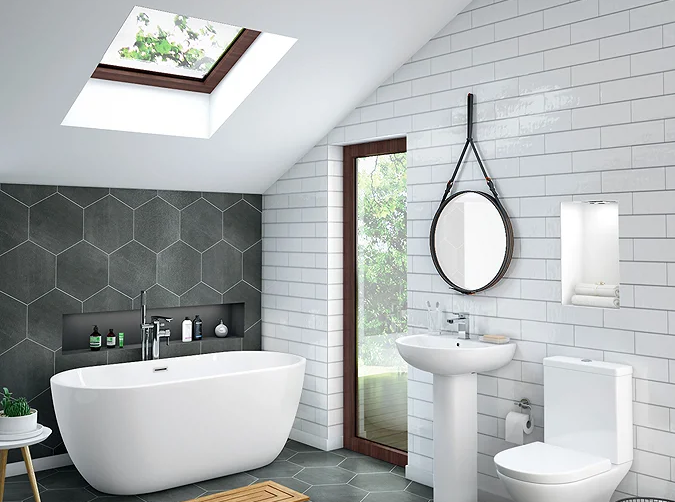
Gervais noted: The reason we invest in Victorian Plumbing is because it’s a well-known online delivery site for all parts of fittings and suchlike. It’s got a very strong record, specifically, it’s got a very strong next-day delivery feature.
What’s been interesting really about the last three years in the company is it’s actually been investing in a very large new distribution centre and that new distribution centre has come on stream. That now allows them to take a lot more market share in the bathroom fittings market but because they have excess space in their distribution centre, they can move into new markets.
You’ve got the ongoing growth of their market share in the bathroom fittings area, but they’ve now moved into the tiles area. The problem with tiles and, indeed, some parts of the furniture market is you can order these things, but you don’t always get them the next day, and so they’re going to be offering next-day service on tiles. That’s quite an innovative feature. Most other tile companies don’t have that in the full range and they’re also moving into the furniture market, where again, many of the major players in that market don’t offer next-day service.
So, we think there’s features of ongoing growth and we think there’s opportunity for them to scale up that growth with these new market sectors. Specifically, we think that with its strong balance sheet, with its ability to generate surplus cash, it’s on a very nice yield at the moment. It may yield something under 4% this year, according to Bloomberg.
Most particularly, we think that it’s undervalued. We think the company share price reflects the history of where we’ve come from with UK equities being perceived as a bit dowdy, small caps being particularly unlucky in terms of share-price overlooked nature during the last five years, as we’ve seen redemptions. So, it’s starting at an undervalued valuation, plus potential for extra growth. It’s a nice combination, we believe.