Norcros plc (LON:NXR) is continuing to strengthen its position in the UK bathroom and kitchen products market, with improving financial performance, strategic acquisitions and market share gains providing reasons for optimism.
In the latest research note on Norcros from Cavendish, dated 7 October 2026, Research Analyst David Buxton reiterates a Buy recommendation and a 380p target price, representing potential upside of approximately 29% from the 294p share price quoted in the report.
The broker believes that Norcros is making encouraging progress despite challenging conditions across the construction and building products sectors. Its growing portfolio of established brands, improving cash generation and ongoing business transformation provide the foundations for further progress.
Norcros Full-Year 2026 Financial Highlights
Norcros delivered a solid performance for the financial year ended March 2026, benefiting from organic market share gains and the acquisition of Fibo.
Key financial highlights include:
- Revenue increased 10.6% to £393.4 million, compared with £355.8 million in FY2025.
- Adjusted EBITDA rose 8.7% to £51.0 million, up from £46.9 million.
- Adjusted operating profit increased 7.9% to £48.0 million.
- Adjusted pre-tax profit improved 8.2% to £40.9 million.
- Adjusted earnings per share increased 7.2% to 35.8p.
- Dividend per share increased 8.7% to 11.3p.
- Free cash flow strengthened to £25.5 million, compared with £11.6 million in the previous year.
- Year-end net debt stood at £65.8 million, reflecting increased borrowing following the Fibo acquisition.
These results demonstrate the group’s ability to deliver growth in a difficult trading environment while investing in its product portfolio and future development.
Strong Brands Supporting Market Share Growth
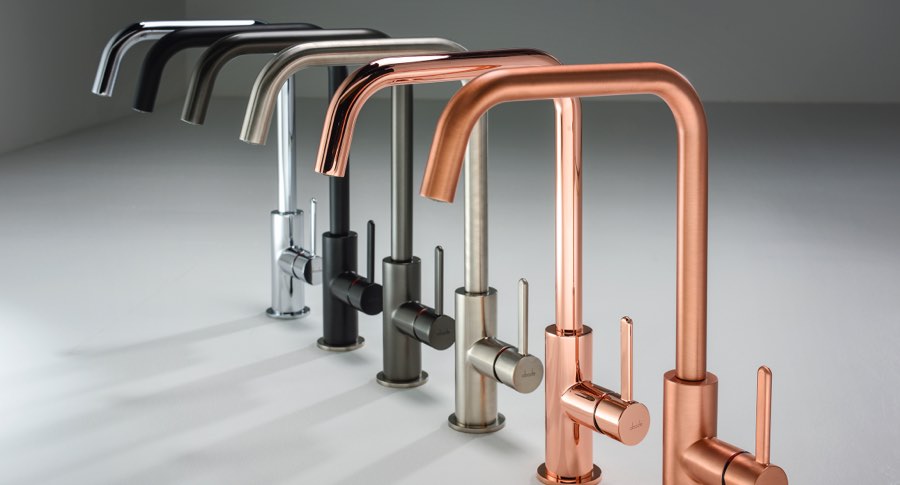
Norcros has built a collection of recognised bathroom brands, including Triton, Merlyn, Vado, Croydex, Grant Westfield and Fibo.
Its emphasis on the mid-market and premium segments provides some protection against the pressures affecting the wider building products industry.
The company has also benefited from new product development, reliable product availability and strong customer service, helping it secure additional business with important customer accounts.
Another positive feature is Norcros’ exposure to the repairs, maintenance and improvement market, which has demonstrated greater resilience than some areas of new-build construction.
Cavendish believes these characteristics leave Norcros well positioned to continue winning market share.
Fibo Acquisition Opens Up Further Growth Opportunities
The acquisition of Fibo, completed in October 2025, represents an important step in the transformation of Norcros.
Fibo specialises in decorative, water-resistant wall panels, an expanding product category that offers an alternative to traditional ceramic tiles.
The acquisition has broadened Norcros’ offering while establishing a stronger commercial presence in continental Europe.
Importantly, Fibo also supports management’s strategy of moving towards a more capital-light business model, reducing dependence on manufacturing-intensive operations.
Alongside this development, Norcros has announced plans to dispose of its remaining South African businesses.
If completed, the disposal would allow management to concentrate resources on its UK and European operations, potentially improving the group’s profitability, financial flexibility and longer-term growth prospects.
Cavendish Sees Significant Valuation Potential
Despite the operational improvements already achieved, Cavendish considers the shares attractively valued.
Research Analyst David Buxton writes:
“The current valuation looks compelling trading at a 41% discount to its peer median.”
The broker’s 380p target price reflects its confidence in further margin improvements, stronger cash generation and the benefits of the group’s evolving business portfolio.
At the 294p reference share price, Norcros trades on approximately 7.0 times forecast earnings for FY2028, according to Cavendish.
The research also highlights the possibility that a recovery in construction activity, potentially supported by lower interest rates, could improve investor sentiment towards the sector.
However, the investment case does not depend entirely on an immediate market recovery. Continued market share gains, improved operational efficiency and further debt reduction could also support progress.
Financial Forecasts Point Towards Continued Growth
Cavendish expects Norcros to maintain its positive earnings trajectory over the coming two financial years.
For the year ending March 2027, the broker forecasts:
- Revenue of £441.4 million, representing growth of 12.2%.
- Adjusted EBITDA of £60.4 million, an increase of 18.4%.
- Adjusted operating profit of £54.1 million.
- Adjusted earnings per share of 39.6p.
- Free cash flow of £27.6 million.
Looking further ahead to FY2028, Cavendish forecasts revenue of £461.0 million, adjusted EBITDA of £63.6 million and adjusted earnings per share of 41.7p.
Net debt is also forecast to decline to £35.5 million by March 2028, supported by ongoing cash generation.
These forecasts suggest that Norcros could emerge from the current challenging market conditions as a more focused and financially flexible business.
What Are the Risks for Norcros Investors?
Although Cavendish maintains a positive outlook, some important risks remain.
Weak construction markets could continue to affect customer demand, while higher operating costs could place pressure on profitability. The successful integration of Fibo and the proposed South African disposal will also be important factors to monitor.
Furthermore, forecast earnings growth and debt reduction are not guaranteed, particularly if wider economic conditions deteriorate.
Final Thoughts
Norcros is making meaningful progress in reshaping its business, with growing market share, a stronger portfolio of brands and improving cash generation supporting its longer-term ambitions.
The acquisition of Fibo has expanded its growth opportunities, while the planned exit from South Africa could further simplify operations and release resources for investment elsewhere.
With Cavendish maintaining its Buy recommendation and 380p target price, the broker sees scope for the shares to deliver a positive return if management continues executing its strategy.
For investors following UK-listed building products companies, Norcros offers an interesting example of a business pursuing operational improvements and strategic growth through a difficult market cycle.