Sintana Energy (LON:SEI) is in focus after the latest research note from Cavendish highlighted fresh momentum around the Mopane discovery offshore Namibia, as well as encouraging strategic developments in Uruguay and Colombia. According to Cavendish’s 30 March 2026 note, the case for Sintana rests not only on the scale of Mopane, but also on the breadth of activity expected across its wider portfolio.
Research analyst James McCormack captures the current investment case neatly in the note’s title, “We know it’s big, but we don’t know if it’s very big”. He also writes that “Galp’s latest estimate, certified by independent auditor Degolyer & MacNaughton, puts gross 3C resources at 1.38bn bbls, up 57% from previous estimates, and implying 67 mmboe net, recoverable to Sintana.” That is a striking upgrade, and it helps explain why Mopane remains central to the story.
Cavendish says Sintana holds a fully carried 4.9% interest in Mopane, and on its numbers that stake alone is worth more than the company’s current share price on a risked basis. The broker sets a 62p target price against a 28.3p share price, while reiterating its Buy recommendation. The note says this equates to 119% upside, with Cavendish valuing Sintana’s interest in Mopane alone at 42p per share on a risked basis.
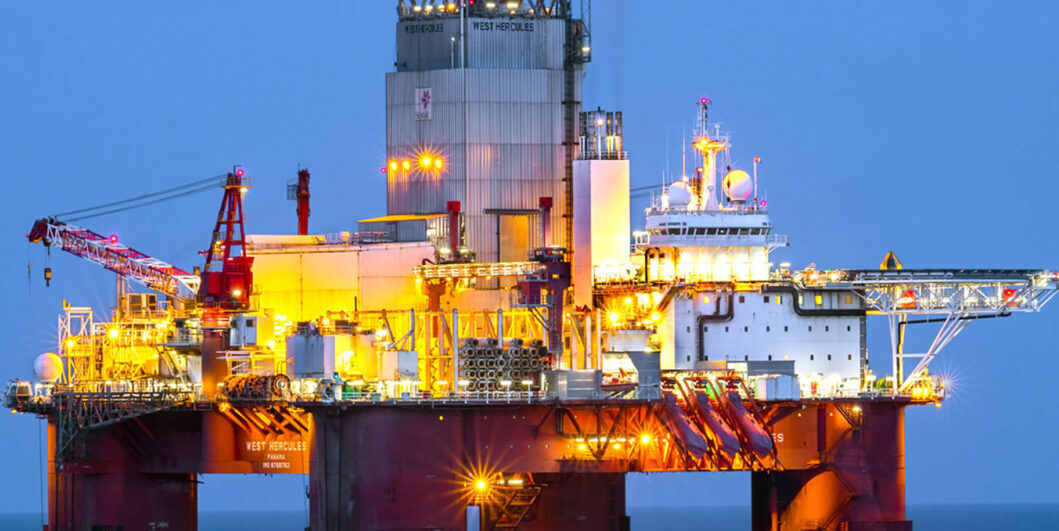
The next stage could be especially important. Cavendish notes that the first of three exploration and appraisal wells at Mopane is due to be spudded this year, with the drilling campaign designed to help define the scale of development ahead of project sanction and field development plan approval in 2028. First oil is anticipated for 2032.
Key highlights from the latest research note
- Gross 3C resources at Mopane increased to 1.38bn barrels, up 57% from previous estimates.
- Sintana’s net recoverable share is estimated at 67 mmboe.
- Cavendish maintains a Buy rating and 62p target price.
- The broker sees 42p per share of risked value in Mopane alone.
- Sintana has received the first US$3 million of a US$9 million settlement with ExxonMobil.
- Sintana reported net cash of £5.5 million and a market capitalisation of £145.0 million in the note.
There is more to the story than Namibia. Cavendish also points to rising industry interest in Uruguay, where QatarEnergy has joined Chevron in farming into Shell licences close to Sintana’s AREA OFF-3. The note stresses that Sintana remains the only junior with exposure to the basin and holds a large net acreage position. Seismic work is already under way on OFF-1, with more than 500 square kilometres of the planned 4,300 square kilometres acquired so far, and key fast-tracked data expected in the fourth quarter of this year.
That matters because it underlines how broad Sintana’s opportunity set has become. Cavendish argues that investors may still be adjusting to the enlarged company following its merger with Challenger, and that this could be one reason the shares still trade at what the broker sees as a meaningful discount to risked NAV.
There is also fresh cash support. Sintana has confirmed receipt of the first US$3 million tranche from the ExxonMobil settlement related to Colombia’s VMM-37 permit. The second US$6 million tranche remains subject to approvals and other requirements, but Cavendish says it is expected before the end of calendar 2026.
The note from Cavendish paints a constructive picture of Sintana Energy. The company offers exposure to a major offshore discovery at Mopane, potential upside from further exploration in Namibia, strategic optionality in Uruguay, and additional financial support from the ExxonMobil settlement. For investors following frontier exploration stories, Sintana looks increasingly like a company with several meaningful catalysts still to come.