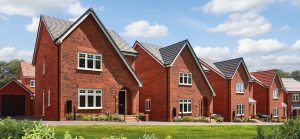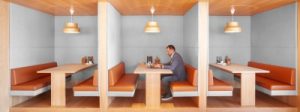
Unite Group PLC (UTG.L), a leading player in the UK’s purpose-built student accommodation (PBSA) sector, presents an intriguing opportunity for investors seeking exposure to the real estate market. As the largest owner, manager, and developer of student housing in the UK, Unite Group manages a portfolio of 72,000 beds across 207 properties, partnering with over 60 universities. With a market capitalization of $2.54 billion, the company is a significant contributor to the UK’s higher education infrastructure.
The current stock price of 493.4 GBp, slightly down by 0.01%, sits within a 52-week range of 419.80 to 595.00 GBp. This positioning provides a potential upside of 11.31%, as predicted by analysts who have set an average target price of 549.20 GBp. The stock’s technical indicators reveal a 50-day moving average of 467.85 GBp and a 200-day moving average of 500.98 GBp, suggesting a recovery potential in the near term.
Revenue growth at 12.40% highlights the company’s ability to expand its influence and market presence, despite a reported negative EPS of -0.98 and a return on equity of -10.77%. These figures indicate that while the company is growing its top line, challenges remain in converting this growth into profitability.
The valuation metrics, particularly the forward P/E ratio at an eye-catching 1,178.18, suggest that investors are betting on future growth and recovery rather than current earnings. This could be a point of caution for some investors, especially when considering the absence of traditional valuation metrics such as PEG, Price/Book, and EV/EBITDA ratios.
Unite Group’s financial health is bolstered by a free cash flow of over £63 million, providing some cushion to navigate market uncertainties and invest in future growth initiatives. Despite the absence of a dividend yield, the company’s commitment to sustainability and becoming net zero carbon by 2030 may appeal to ESG-focused investors.
From an analyst perspective, the stock is garnering mixed reviews with 7 buy ratings, 6 hold ratings, and 2 sell ratings. This distribution reflects a cautious optimism about the company’s future performance in a sector that is essential yet subject to fluctuating demand patterns due to external factors like changes in university enrollment and international student mobility.
The RSI (Relative Strength Index) of 31.71 indicates that the stock is nearing oversold territory, potentially signaling a buying opportunity for value-oriented investors. Meanwhile, the MACD and signal line readings suggest a positive momentum shift could be on the horizon.
For investors considering a stake in Unite Group, the company’s strategic focus on high-quality, affordable student accommodation backed by a robust operational framework provides a solid foundation. However, the high forward P/E ratio and negative earnings indicate that patience and a long-term perspective will be key to realizing potential gains.
As the UK continues to attract international students and expand its educational offerings, Unite Group PLC stands at the forefront, ready to capitalize on these trends. Investors will be keenly watching how the company navigates its path to profitability while upholding its commitments to sustainability and stakeholder satisfaction.