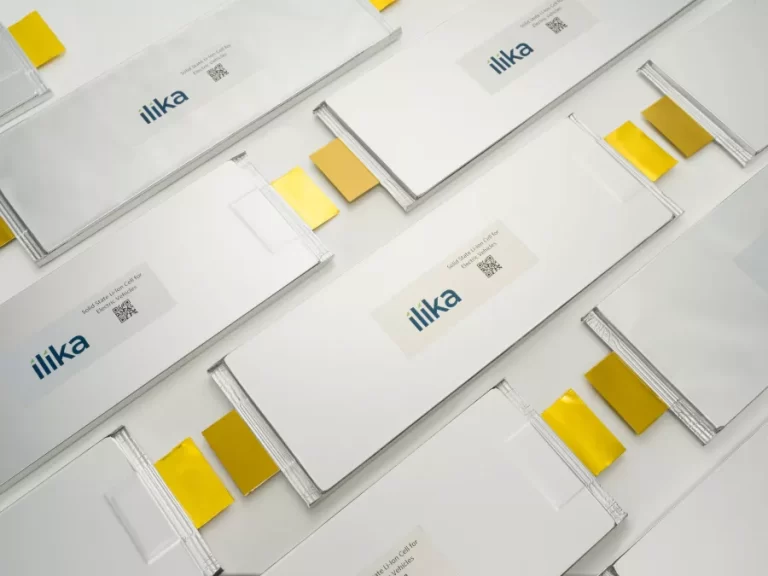
Ilika plc (LON:IKA) is opening up new opportunities for its solid-state battery technology with the launch of ORKA, a new brand targeting underwater applications. The development marks another step in the company’s efforts to commercialise its Goliath battery platform beyond the electric vehicle market.
In the latest research note from Cavendish, dated 22 October 2026, research analyst Ian McInally highlights the growing potential for Ilika’s technology across marine, defence and other specialist markets.
Cavendish maintains its Buy recommendation and 118p share price target, representing a potential upside of 424% against the 22.5p share price quoted in the research note.
ORKA Opens Up Opportunities in Underwater Technology
Ilika’s newly launched ORKA brand is designed to address demand for pressure-tolerant batteries used in autonomous underwater vehicles (AUVs).
These unmanned vehicles are becoming increasingly important for underwater surveying, deep-sea mapping and monitoring critical infrastructure, including fibre-optic cables and gas pipelines.
They also have significant defence applications, where dependable energy storage can be essential for carrying out operations in challenging underwater environments.
One of the potential advantages of Ilika’s solid-state battery technology is its suitability for demanding operating conditions.
According to Cavendish, Ilika’s batteries can operate at depths of up to 6,000 metres while offering longer endurance. Pressure-tolerant battery technology can also remove the need for heavy metal pressure vessels, potentially reducing the weight and complexity of underwater systems.
These characteristics could make ORKA an interesting proposition for developers of next-generation underwater vehicles.
Cavendish Highlights Growing Marine and Defence Potential
Research analyst Ian McInally identifies underwater applications as a potentially important addition to Ilika’s commercialisation strategy.
As McInally writes in the latest Cavendish research note:
“Mobile energy storage also supports many modern defence applications, including AUVs, and underwater applications could represent another significant market opportunity.”
The observation reflects the wider opportunity for Ilika to introduce its Goliath technology into markets beyond electric vehicles.
Cavendish highlights growing interest in applications including e-bikes, defence equipment and marine technology, which could potentially offer faster routes to commercialisation than the automotive sector.
Although the scale and timing of these opportunities remain uncertain, diversifying into specialist markets could provide additional ways for Ilika to build commercial relationships and demonstrate the capabilities of its technology.
Defence Sector Developments Add Momentum
Ilika has also been strengthening its position within the defence sector.
In March 2026, the company reported positive feedback from a UK defence agency following battlefield-safety testing of its batteries.
The feedback highlighted the potential suitability of the technology for high-risk, mission-critical applications, although the research note does not identify a resulting commercial contract.
Another development is the appointment of retired Major General Robin Anderton-Brown as a defence sector adviser.
Cavendish believes this appointment should help strengthen Ilika’s access to the defence market, potentially supporting further engagement with organisations seeking advanced energy storage solutions.
Together with the ORKA launch, these developments demonstrate how Ilika is exploring several potential commercial markets for its solid-state battery technology.
Ilika Financial Outlook and Cavendish Valuation
While the latest research focuses primarily on commercial opportunities, Cavendish also provides financial forecasts that illustrate the company’s expected development.
Key financial figures and estimates from Cavendish:
- FY2026 reported revenue: £1.1 million.
- FY2027 forecast revenue: £2.0 million.
- FY2028 forecast revenue: £2.9 million.
- FY2026 adjusted EBITDA loss: £6.2 million.
- FY2027 forecast adjusted EBITDA loss: £6.9 million.
- FY2028 forecast adjusted EBITDA loss: £5.5 million.
- Market capitalisation: £44.8 million, based on the research note.
- Net cash: £5.3 million, as stated in the research note.
- Cavendish share price target: 118p, with a Buy recommendation.
The forecasts suggest that Cavendish expects revenue to increase over the coming financial years, although Ilika is also expected to remain loss-making through FY2028.
This highlights the importance of converting technological progress and potential market opportunities into sustainable commercial revenue.
The broker’s 118p target represents a substantial premium to the share price at the date of its research. However, achieving that valuation is not guaranteed and will depend on the company’s progress and wider market conditions.
Why ORKA Could Be Important for Ilika
The significance of ORKA extends beyond launching a new battery brand.
For Ilika, the development represents another opportunity to demonstrate how its Goliath platform could address specialist energy storage requirements in markets where battery performance and operating conditions are particularly demanding.
Underwater vehicles require reliable power to complete tasks independently, sometimes at considerable depths and over extended periods.
If Ilika can successfully translate its technology into commercially viable products for these applications, marine and defence markets could become useful contributors to its wider commercialisation strategy.
Nevertheless, the opportunity remains at an early stage, and the Cavendish note does not provide confirmed ORKA customer orders or revenue projections specifically attributable to underwater applications.
Final Thoughts
Ilika’s launch of ORKA is a positive development in its efforts to broaden the commercial applications of solid-state battery technology.
With growing interest across marine, defence and other specialist sectors, the company is exploring potential routes to market that could complement its longer-term automotive ambitions.
The positive feedback from defence-related testing, combined with the appointment of an experienced defence adviser, provides further context for Cavendish’s constructive outlook.
Cavendish’s Buy recommendation and 118p target price underline the broker’s confidence in Ilika’s longer-term potential, although meaningful commercial progress and continued financial investment will be important factors to monitor.
For Ilika, the next important step will be turning the opportunities identified for ORKA and Goliath into tangible commercial agreements and revenue growth.