Physitrack (PTRK.ST) has reported its strongest quarterly revenue growth since 2023, with third-quarter sales rising 14% year on year as its new Electronic Medical Records (EMR) platform attracts encouraging early interest from healthcare providers.
The latest research note from Redeye Equity Research, dated 20 October 2026, highlights improving sales momentum, continued profitability and early progress in the company’s expansion into the US healthcare market.
Research analyst Jessica Grunewald describes the quarterly performance as mixed against expectations, with revenue exceeding forecasts while annual recurring revenue (ARR) came in below estimates.
Nevertheless, the successful early launch of Physitrack’s EMR platform provides a potentially important new opportunity for the business.
Physitrack Q3 2026 financial highlights
Physitrack’s third-quarter results demonstrated a return to stronger revenue growth, supported by its core Lifecare division.
- Revenue: Increased 14% year on year to €3.63 million, exceeding Redeye’s €3.51 million forecast by 3%.
- Adjusted EBITDA: Reached €1.12 million, broadly in line with expectations.
- Adjusted EBITDA margin: Stood at 30.8%.
- Group annual recurring revenue: Reached approximately €13.5 million, slightly below the previous quarter.
- Lifecare revenue: Increased 15% year on year to €3.29 million.
- Lifecare ARR: Increased 9% year on year to €12.8 million.
- Operating cash flow: Reached €1.13 million during the quarter.
- Free cash flow: Totalled approximately €0.2 million.
- Net debt: Reduced to €3.72 million.
The revenue improvement represents the company’s strongest annual quarterly growth since 2023, supported by increased pricing and continued demand for its digital healthcare software.
EMR launch attracts more than 480 clinics
One of the most encouraging developments highlighted by Redeye is the early response to Physitrack’s new EMR platform.
Launched into early access on 28 September 2026, the platform had attracted more than 480 clinics representing over 4,700 users by mid-October.
This compares with approximately 100 clinics and 500 users at launch.
The new platform represents an important expansion of Physitrack’s existing software offering, moving beyond digital rehabilitation tools towards becoming a central system for managing clinical information and workflows.
Redeye identifies an addressable market opportunity of approximately $1.4 billion to $1.6 billion.
The EMR platform is being offered free during the early-access period, with paid subscriptions scheduled to begin on 1 January 2027.
While early adoption has been encouraging, converting users into paying customers will be an important measure of future commercial success.
Lifecare growth supported by pricing and customer retention
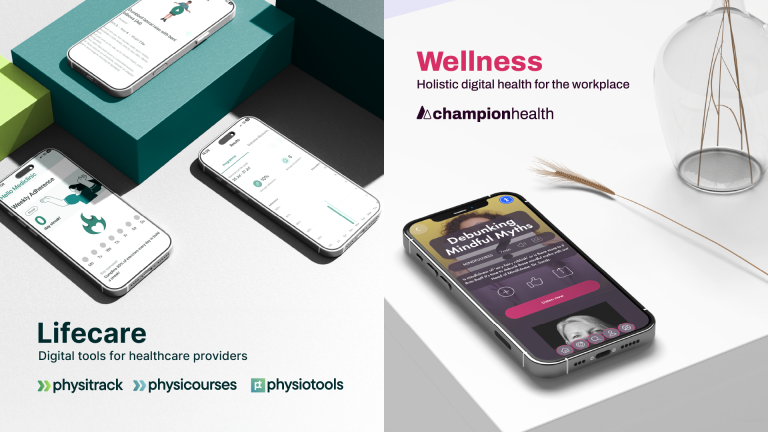
Physitrack’s Lifecare division remained the main driver of group revenue growth.
Revenue increased 15% to €3.29 million, ahead of Redeye’s forecast of €3.21 million.
The core Physitrack product recorded growth of 26%, while the division’s annual recurring revenue increased to €12.8 million.
A price increase introduced in May 2026 contributed to improved revenue per licence.
Average revenue per licence rose 11% year on year to €190, while monthly customer churn remained stable at 1%.
Redeye also noted that licence numbers had increased for two consecutive quarters despite the price increase.
These developments suggest Physitrack has been able to achieve higher revenue per licence while maintaining a relatively stable customer base.
However, investment in the US business contributed to higher operating costs, with Lifecare’s adjusted EBITDA margin declining to 42% from 48% in the corresponding period last year.
US healthcare expansion provides further opportunities
Physitrack’s progress in the United States was another important theme in the research.
During September, the company was selected by two US healthcare systems following competitive processes.
One agreement involves a large academic healthcare organisation selecting Physitrack as its preferred digital rehabilitation provider.
The potential contract value is approximately $390,000, with revenue expected from 2027, although contracting remained ongoing at the time of the research.
A second agreement involves a metropolitan healthcare system adopting Physitrack across 86 practitioners, replacing two existing providers.
The deployment includes integration with Epic and MyChart systems, with implementation expected during the fourth quarter of 2026.
Although the immediate financial contributions are relatively modest, Redeye considers these customer relationships important references for future expansion.
Redeye sees a return to growth despite softer ARR
Research analyst Jessica Grunewald writes:
“The Q3 report supports our view that Physitrack is a profitable, cash-generative SaaS business that is growing again”
The positive assessment reflects accelerating revenue growth and continued operating cash generation.
However, Redeye also identifies challenges within Physitrack’s Wellness division.
Wellness ARR declined to approximately €0.7 million following the loss of a major enterprise customer, contributing to group ARR falling short of expectations.
Despite this setback, the division remained profitable, with an adjusted EBITDA margin of 38%.
Redeye expects only limited changes to its overall financial estimates, with potential improvements in Lifecare revenue broadly offset by weaker Wellness expectations.
Final Thoughts
Physitrack’s third-quarter results present an encouraging picture of improving revenue momentum, ongoing profitability and expanding opportunities in digital healthcare.
The 14% increase in quarterly revenue, positive operating cash flow and early interest in the EMR platform provide several reasons for optimism.
With more than 480 clinics participating in EMR early access and new healthcare customer relationships emerging in the United States, the company has opportunities to broaden its commercial offering.
However, the softer ARR performance and increased investment costs underline the importance of converting new product adoption into sustainable recurring revenues.
For investors following Physitrack, the coming quarters will be particularly important as the company begins commercialising its EMR platform and seeks to translate its growing US presence into additional revenue.