GSK plc (LON:GSK) has announced its Q3 results.
Strong Q3 performance and continued momentum
| Strong Specialty Medicines performance drives sales and core operating profit growth | |
| • | Total Q3 sales £8.9 billion +4% AER; +5% CER |
| • | Specialty Medicines sales £3.9 billion (+15%); HIV sales £2.1 billion (+10%), Respiratory, Immunology & Inflammation £1.1 billion (+21%); Oncology £0.6 billion (+23%) |
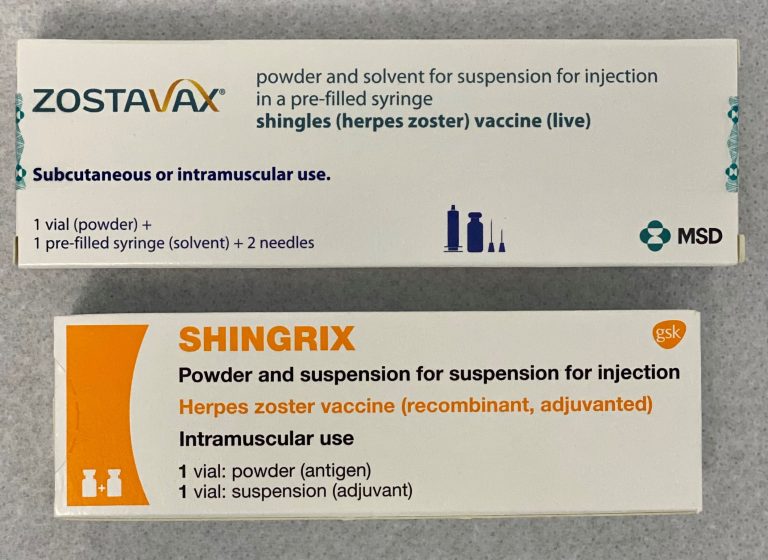
| • | Vaccines sales £2.6 billion (-2%); Shingrix £0.8 billion (-5%); Meningitis vaccines £0.6 billion (+12%); and Arexvy £0.2 billion (-24%) |
| • | General Medicines sales £2.4 billion (stable); Trelegy £0.8 billion (+8%) |
| • | Total operating profit -16% and Total EPS -21% driven by Major restructuring charges of £328 million related to the Accelerate Growth programme and lower other net operating income, partly offset by Core operating profit growth |
| • | Core operating profit +5% and Core EPS +1% reflecting higher sales, favourable product and regional mix and higher royalty income, partly offset by increased investment in R&D and new asset launches and higher finance costs |
| • | Cash generated from operations of £3.1 billion with free cash flow of £2.1 billion |
| (Financial Performance – Q3 2026 results unless otherwise stated, growth % and commentary at CER as defined on page 43. The quarter and year to date adverse currency impact on AER versus CER primarily reflected the strengthening of Sterling against the USD. See page 8 for further details.) | |
| Q3 2026 | Year to date | |||||
| £m | % AER | % CER | £m | % AER | % CER | |
| Turnover | 8,887 | 4 | 5 | 24,925 | 4 | 5 |
| Total operating profit | 2,127 | (18) | (16) | 4,901 | (28) | (25) |
| Total operating margin % | 23.9% | (6.4ppts) | (6.1ppts) | 19.7% | (8.7ppts) | (8.2ppts) |
| Total EPS | 38.5p | (23) | (21) | 92.5p | (26) | (23) |
| Core operating profit | 3,076 | 3 | 5 | 8,526 | 5 | 7 |
| Core operating margin % | 34.6% | (0.3ppts) | (0.1ppts) | 34.2% | 0.3ppts | 0.7ppts |
| Core EPS | 54.6p | (1) | 1 | 151.6p | 4 | 6 |
| Cash generated from operations | 3,122 | 24 | 7,378 | 18 | ||
| Continued pipeline progress: | |
| • | Hibsago approved in US and Japan, with data showing unprecedented functional cure rates and potential to redefine treatment of chronic hepatitis B |
| • | Jemperli approved in US as first immunotherapy for adults with dMMR/MSI-H locally advanced rectal cancer |
| • | Positive registrational data for Jideytro in first-line ROS1-positive non-small cell lung cancer (approved in US in second-line in July) |
| • | Promising first global data for Ris-Rez in lung cancer; and positive phase I data for Mo-Rez in ovarian cancer |
| • | Shingrix pre-filled syringe approved in Japan, simplifying administration |
| • | mRNA seasonal influenza (flu) vaccine phase III trial initiated, following positive phase II data |
| • | On track to start 22 phase III trials in 2026 with 18 starts to date |
| Growth outlooks: | |
| • | 2026 guidance reaffirmed with expected growth in: turnover 3% to 5%; Core OP 7% to 9%; Core EPS 7% to 9% |
| • | On track for 2031 sales outlook of more than £40 billion |
| • | Operating margin stable to improving through dolutegravir loss of exclusivity period of 2028-2030 |
| Shareholder returns: | |
| • | Q3 2026 dividend of 17p declared; 70p expected for full year 2026 |
Luke Miels, Chief Executive Officer, GSK:“GSK has delivered another strong quarter, with our key growth drivers and new launches performing well. We remain focused on operational delivery, execution and accelerating R&D. Over recent months we have received 3 new specialty medicine approvals in the US: Hibsago, which has the potential to transform the treatment of chronic hepatitis B; Jideytro in non-small cell lung cancer; and Jemperli in rectal cancer. More broadly, in the late-stage portfolio, we are on track to start 22 phase III trials this year.”
Guidance all at CER. The Total results are presented in summary above and on page 7 and Core results reconciliations are presented on pages 16 and 18. Core results are a non-IFRS measure that may be considered in addition to, but not as a substitute for, or superior to, information presented in accordance with IFRS. The following terms are defined on pages 43-44: Core results, AER% growth, CER% growth and other non-IFRS measures. GSK provides guidance on a Core results basis only for the reasons set out on page 14. All expectations, guidance and outlooks regarding future performance and dividend payments should be read together with ‘Guidance and outlooks, assumptions and cautionary statements’ on pages 45-46. Abbreviations are defined on page 49.
2026 Guidance
GSK reaffirms its full-year 2026 guidance at constant exchange rates (CER).
| Turnover is expected to increase between 3% to 5%, at the upper half of the range |
| Core operating profit is expected to increase between 7% to 9%, at the upper half of the range |
| Core earnings per share is expected to increase between 7% to 9%, at the lower half of the range |
This guidance is supported by the following turnover expectations for full-year 2026 at CER.
| Specialty Medicines | – | expected increase at a low double-digit percentage |
| Vaccines | – | expected to be broadly stable to an increase at a low single-digit percentage |
| General Medicines | – | expected decline of a mid-single digit to low single-digit percentage |
Core operating profit is expected to grow at the upper half of the 7 to 9 per cent range at CER. GSK continues to expect to deliver gross margin accretion due to improved product mix from Specialty Medicines growth and continued operational efficiencies. In addition, GSK anticipates further leverage in Operating profit as we accelerate ongoing productivity initiatives and take a returns-based approach to SG&A investments, with SG&A expected to be broadly stable year-on-year. R&D is expected to grow significantly ahead of sales as we accelerate investments in the pipeline as part of the Accelerate Growth programme while driving operational efficiencies. Royalty income is expected to be around £900 million.
Core earnings per share is expected to increase at the lower half of the 7 to 9 per cent range at CER, reflecting higher interest charges of around £700-750 million, including the impact of the Nuvalent acquisition, and the tax rate which is expected to rise to around 17.5%, offset by the expected benefit from the share buyback programme. Expectations for non-controlling interests remain unchanged relative to 2025.
Agreement with US Government to lower the cost of prescription medicines for American patients
As previously announced, on 19 December 2025, GSK entered into an agreement with the US Administration to lower the cost of prescription medicines for American patients and exclude both GSK and ViiV Healthcare from Section 232 tariffs for three years. On 9 April 2026, GSK, ViiV Healthcare, and the US Government entered into a definitive agreement reflecting Section 232 tariff relief through 20 January 2029 (subject to implementation and ongoing compliance). As part of that implementation, GSK and ViiV Healthcare each signed a GENEROUS Model Manufacturer Participation Agreement with the Centers for Medicare and Medicaid Services effective 15 June 2026. With these agreements GSK and ViiV Healthcare have committed certain products to participate in the voluntary GENEROUS Model. GSK and ViiV have also entered into GENEROUS Model Supplemental Rebate Agreements with several interested states and will work with the other states going forward to execute Supplemental Rebate Agreements as requested. Our full year guidance is inclusive of the expected impact of these agreements.
Dividend policy
The Dividend policy and the expected pay-out ratio remain unchanged. Consistent with this, GSK has declared a dividend for Q3 2026 of 17p per share. GSK’s future dividend policy and guidance regarding the expected dividend pay-out in 2026 are provided on page 30.
GSK completed the £2 billion share buyback programme announced in FY 2024 in Q2 2026.
Exchange rates
If exchange rates were to hold at the closing rates on 30 September 2026 ($1.33/£1, €1.17/£1 and Yen 209/£1) for the rest of 2026, the estimated impact on 2026 Sterling turnover growth for GSK would be -1% and if exchange gains or losses were recognised at the same level as in 2025, the estimated impact on 2026 Sterling Core Operating Profit growth for GSK would be -3%.
Results presentation
A conference call and webcast for investors and analysts of the quarterly results will be hosted by Luke Miels, CEO, at 12:00 GMT (08:00 EDT) on 28 October 2026. Presentation materials will be published on www.gsk.com prior to the webcast and a transcript of the webcast will be published subsequently.
Notwithstanding the inclusion of weblinks, information available on the company’s website, or from non GSK sources, is not incorporated by reference into this Results Announcement.