EnQuest plc (LON:ENQ), an independent energy company listed on the London Stock Exchange, has announced that it has entered into an agreement to sell the Company’s UK upstream business and associated infrastructure, through the sale of EnQuest Britain Limited to NEO NEXT+ Energy Upstream UK Limited for total consideration of up to US$960 million. The total consideration comprises:
- US$840 million in upfront cash consideration to be paid on completion, subject to customary closing adjustments, including working capital, together with
- Up to US$120 million contingent cash consideration, as described further below.
The Proposed Disposal is based on an economic effective date of 1 January 2027 and is subject to customary conditions, including inter alia regulatory approvals, and completion of the Company’s acquisitions of participating interests in four PSCs in Malaysia, as announced on 10 June 2026 (the “Proposed Acquisitions”), and which remain on track to complete on 31 December 2026.
Together, the Proposed Disposal and the Proposed Acquisitions continue EnQuest’s strategic pivot to South East Asia as its primary operating region, creating a low-cost, highly resilient platform from which to pursue further near-term capital-efficient organic and inorganic growth. Following completion of the Proposed Disposal, EnQuest intends to repay debt drawn in connection with the Proposed Acquisitions, while retaining significant liquidity and financial flexibility to pursue material organic growth and further acquisition opportunities across the region.
Amjad Bseisu, Chief Executive Officer, EnQuest, commented:
“This transaction marks a major step forward in EnQuest’s strategic evolution. From our genesis as a UK North Sea oil and gas specialist, and following many years of investment and top-quartile operational delivery in the UK North Sea, we are executing on our strategy to maximise value from our UK business at an attractive valuation of up to US$9/boe of 2P reserves.
Together with our recent transformational acquisitions in Malaysia and the strong growth we continue to deliver across the region, the Proposed Disposal positions our high-quality South East Asian portfolio at the core of EnQuest, where we see compelling opportunities to invest, build scale and create long-term shareholder value.
The resulting business will have a materially lower cost base and significantly enhanced balance sheet strength to pursue both organic investment and further value-accretive acquisitions across South East Asia, while supporting sustainable shareholder returns.
We are immensely proud of what our teams have achieved in the UK and believe that NEO NEXT+’s combination of scale and track record as a leading North Sea operator, and diverse asset portfolio will enhance career opportunities for our people. We are committed to working closely with NEO NEXT+, our employees, joint venture partners and other stakeholders to ensure an orderly transition.”
Strategic repositioning towards South East Asia
The Board of Directors of EnQuest believes the Proposed Disposal represents a significant step forward in the continued strategic evolution of EnQuest, crystallising material value from the Company’s UK upstream portfolio, significantly strengthening the EnQuest Group’s capital structure and completing EnQuest’s repositioning towards South East Asia.
The Board considers that the Proposed Disposal and the Proposed Acquisitions, together:
- Establish South East Asia as EnQuest’s primary operating region, where the Company sees significant opportunities for further high-return, capital-efficient growth;
- Maintain EnQuest’s established focus on operatorship and highly tangible reserves, deploying the Group’s operating capabilities and experienced asset teams to enhance value via a number of measures, including recovery factor improvement and conversion of 2C resources; and
- Provide a strengthened platform from which to accelerate further organic growth initiatives in South East Asia and capitalise on further inorganic growth opportunities across the region.
Low-cost, highly resilient operating portfolio with potential for faster growth
On a 2025 net participating interest basis, following completion of the Proposed Disposal and the Proposed Acquisitions, the remaining EnQuest portfolio is expected to benefit from:
- c.70 Kboed South East Asia business, with unit opex of c.US$11/boe, a reduction of c.57% against the Group’s 2025 unit opex of US$25/boe, generating pro forma EBITDA of c.$500 million;
- In 2026, production has grown further via the addition of low-cost Seligi 1b gas volumes;
- Substantial capital-efficient growth potential, including opportunities to leverage existing infrastructure;
- South East Asia capital investment is focused on high-return production enhancement activity, with minimal infrastructure investment required;
- A significant improvement in pro forma net debt to EBITDA of 0.5-0.7x at 31 December 2025, reduced from pro forma 1.1x.
Significantly enhanced financial strength
The Board expects that the following benefits will result from the Proposed Disposal:
- Material cash proceeds that will significantly strengthen EnQuest’s balance sheet, delivering greater financial flexibility and significantly reduced financing costs;
- Undrawn RBL capacity in excess of US$400 million that provides strong transactional liquidity;
- Increased capacity to fund organic and inorganic growth opportunities that support future shareholder returns; and
- A substantial reduction in future decommissioning liabilities.
The Proposed Disposal
EnQuest Group Holdings Limited (the “Seller”) and NEO NEXT+ have entered into a share purchase agreement dated 17 November 2026 for the purposes of implementing the Proposed Disposal (the “Agreement”).
The Board believes the Proposed Disposal represents a significant step in the continued strategic evolution of EnQuest, crystallising material value from the Company’s UK upstream portfolio and associated tax asset, which significantly strengthens the Group’s capital structure and completes the strategic repositioning of the business towards South East Asia.
The Board considers the Proposed Disposal is in the best interests of the Company and its shareholders.
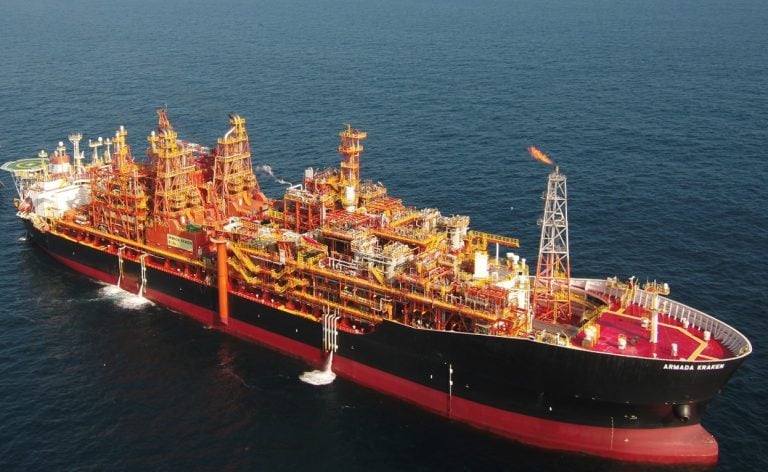
The Proposed Disposal will involve the sale of all of the issued shares of EnQuest Britain Limited, which through its subsidiaries holds EnQuest’s UK upstream assets, including Magnus, Kraken and the Greater Kittiwake Area (operated), Golden Eagle (non-operated) and the undeveloped Bressay field and Bentley discovery. It also holds the Group’s UK decommissioning and UK midstream assets, including EnQuest’s operating interest in the Sullom Voe Terminal, the Northern Leg Gas Pipeline and the Ninian Pipeline system. Employees supporting these operations will transfer with EnQuest Britain Limited as a result of the Proposed Disposal.
For the year ended 31 December 2025, EnQuest’s UK upstream assets contributed 31,122 Boepd of average net production (92% liquids and 8% gas). As at 31 December 2025, the UK upstream portfolio comprised approximately 122 MMboe of 2P reserves and 308 MMboe of 2C Resources.
The carrying value of the gross assets held by EnQuest Britain Limited represented US$3,129 million as at 31 December 2025. Net assets represented US$171 million at the same date, inclusive of total UK decommissioning, lease and other liabilities totalling US$2,125 million, which transfer to the Offeror as part of the Proposed Disposal, along with net intercompany balances payable to the Remaining Business (as defined below). For the year ended 31 December 2025, EnQuest Britain Limited generated a US$2 million loss after tax, reflecting the US$124 million non-cash tax charge associated with the extension to the Energy Profits Levy within the UK North Sea tax regime.
Following completion of the Proposed Disposal, the EnQuest Group will comprise interests in production, development and exploration assets in Malaysia, Vietnam, Brunei and Indonesia, held under EnQuest Global Ltd, as well as Veri Energy, a wholly owned subsidiary of EnQuest, and associated CCUS interests (the “Remaining Business”), which sit outside the Proposed Disposal perimeter. EnQuest Britain Limited’s intercompany balances (US$833 million in aggregate as at 31 December 2025), including the Group’s US$675 million US Dollar High Yield Bond, will be retained in the Remaining Business, post-completion.
Following completion of the Proposed Disposal, it is expected that the composition of the Board will remain unchanged.
Consideration
Total consideration of up to US$960 million will be payable to the Seller pursuant to the Agreement, comprising:
- US$840 million cash consideration, subject to closing adjustments, including net working capital, payable on completion of the Proposed Disposal; plus
- A contingent cash consideration of up to US$120 million, payable on 1 March of the relevant year through any combination of:
- Oil price contingent payment: Capped at US$120 million and calculated annually as US$0.2 per barrel of actual oil production for every US Dollar by which the average price exceeds US$75/bbl Brent in 2027, 2028 and 2029; and/or
- Energy Profits Levy contingent payment: Capped at US$100 million and payable on a sliding scale based on the abolition or reduction of the EPL due to a change in legislation between 1 January 2027 and 31 December 2029.
Total Contingent Consideration payable under either mechanism pursuant to the Agreement is capped at US$120 million in aggregate.
A deposit of US$67.2 million is due to be paid by NEO NEXT+ on signing. The deposit (plus interest) must be returned in certain circumstances related to satisfaction of the conditions. The deposit will be deducted from the cash consideration as a closing adjustment.
Strategic Rationale
The Proposed Disposal represents a significant repositioning of EnQuest, continuing the Company’s transformation from a UK-focused operator into a business focused on high-quality assets in South East Asia, underpinned by a simple, strong capital structure. Following completion of both the Proposed Acquisitions and the Proposed Disposal, EnQuest will be a significant operator of scale, with its upstream portfolio focused solely on its 97% operated 2P asset base in South East Asia.
In recent years, in response to an uncertain investment environment within the UK, EnQuest has established a growing opportunity set in South East Asia, where the Group sees greater potential to deploy capital, build scale and deliver sustainable long-term growth. This changing balance of opportunity has informed EnQuest’s decision to reshape its portfolio and increase its strategic focus on the region, recycling invested capital from a high-tax, low-return basin into a high-growth region that is structurally short on energy.
Against this backdrop, the Proposed Disposal enables EnQuest to deliver on its strategic objective of realising material value from its UK business and associated tax asset, at an attractive multiple of up to US$9/boe of 2P reserves (estimated at 31 December 2026, assuming full consideration payable), while retaining exposure to potential upside from higher oil prices and if favourable changes to the UK fiscal regime were made via the repeal or reduction of the Energy Profit Levy.
Employees supporting EnQuest’s UK operations will transfer as a result of the Proposed Disposal. We believe that the transaction will be positive for our staff onshore in Aberdeen and on Shetland and offshore in the North Sea, enhancing career opportunities with one of the UK’s largest operators.
Following completion, the Proposed Disposal is expected to materially further strengthen EnQuest’s balance sheet, lower its operating cost base and cash flow breakeven, and provide increased capacity for organic and inorganic growth and shareholder returns. The proceeds from the Proposed Disposal are expected to be used to repay amounts drawn under the Group’s RBL facility, whilst maintaining significant liquidity to fund further near-term growth opportunities in South East Asia.
Conditions to completion
Completion of the Proposed Disposal is expected in the first quarter of 2027, subject to conditions set out in the Agreement, including:
- Receipt of applicable regulatory approvals, including NSTA and NSIA approval and CMA clearance;
- Completion of the Company’s previously announced Proposed Acquisitions of participating interests offshore Malaysia, which EnQuest continues to expect to complete on 31 December 2026; and
- Other customary approvals and consents including, amongst others, RBL lender consent and replacement of UK Decommissioning Security Agreements.
Regulatory
The Proposed Disposal represents a ‘significant transaction’ for the purposes of the UK Listing Rules made by the Financial Conduct Authority (the “FCA”) (the “UKLRs”) and is therefore notifiable in accordance with Chapter 7 of the UKLRs. In accordance with the UKLRs, the Proposed Disposal is not subject to approval by the Company’s shareholders. The Appendix to this announcement contains the risk factors associated with the Proposed Disposal. The further information required by UKLR 7 Annex 2 Part 2 and Part 3 will be set out in a subsequent announcement as soon as possible and in any event prior to completion of the Proposed Disposal.
As the Proposed Disposal represents a significant new factor for the purposes of the Prospectus Rules: Admission to Trading on a Regulated Market sourcebook, a supplementary prospectus for the purposes of the combined prospectus and shareholder circular published on 24 July 2026 in connection with the Proposed Acquisitions (the “July Prospectus”) will be published in due course (the “Supplementary Prospectus”). Further announcements will be made as applicable.