For investors keen on the UK residential construction sector, Berkeley Group Holdings (BKG.L) presents a complex but intriguing opportunity. Despite its solid market position and diverse brand portfolio, the current data paints a mixed picture for potential investors. Let’s delve into the details of what Berkeley Group has to offer and the challenges it faces.
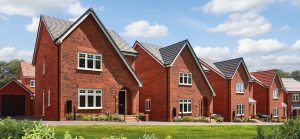
Operating within the Consumer Cyclical sector, Berkeley Group is a significant player in the Residential Construction industry in the United Kingdom. With a market capitalization of $3.31 billion, it stands as a substantial entity contributing to the development of homes and neighborhoods across the UK. Berkeley operates under several brands, including Berkeley, St Edward, St George, St James, St Joseph, and St William, each contributing to its diverse residential-led mixed-use developments.
Currently priced at 3,666 GBp, Berkeley’s stock has experienced a marginal decline of 0.02%, reflecting a price change of -72.00 GBp. The 52-week trading range of 3,104.00 to 4,434.00 GBp highlights the stock’s volatility and the broader market uncertainty affecting the construction sector. The stock’s technical indicators, such as the 50-day and 200-day moving averages, sit at 3,384.28 GBp and 3,550.35 GBp, respectively, indicating a recent downward trend.
Valuation metrics raise some eyebrows, with the trailing P/E ratio not available and a staggering forward P/E of 1,318.57, suggesting market expectations of future earnings are high. Investors might find the lack of data on other valuation metrics like PEG ratio, Price/Book, and Price/Sales ratios concerning, as these are critical for a comprehensive assessment of the company’s financial health.
Berkeley’s performance metrics further complicate the investment narrative. Revenue growth has slightly contracted by 0.30%, and net income data is unavailable, potentially indicating challenges in profitability. However, the company maintains a reasonable EPS of 3.31 and a respectable return on equity of 8.84%, suggesting some level of operational efficiency. The free cash flow position of £353 million is a positive sign, providing the company with financial flexibility amid market fluctuations.
Dividend-seeking investors might be disappointed by Berkeley’s current yield of 0.00% and a payout ratio of 0.00%, indicating that the company is not returning profits to shareholders in the form of dividends at present. This could be a strategic decision to reinvest earnings into growth or manage liquidity more conservatively.
Analyst sentiment towards Berkeley is cautious, with a consensus leaning towards hold ratings: 7 buy, 9 hold, and 4 sell. The target price range of 2,800.00 to 4,301.00 GBp, with an average of 3,636.50 GBp, suggests limited potential upside, with current prices already hovering near this average target. The potential downside of -0.80% further underscores the market’s tepid outlook.
Technical indicators like the RSI (14) at 37.89 suggest the stock might be nearing oversold territory, potentially signaling a buying opportunity for risk-tolerant investors. Meanwhile, the MACD at 95.94 and the Signal Line at 64.48 offer a mixed signal, neither strongly bullish nor bearish.
Berkeley Group’s strategic focus on residential-led mixed-use development and its partnerships in affordable housing position it well for long-term growth. However, macroeconomic challenges, including interest rate fluctuations, regulatory changes, and market demand dynamics, could weigh heavily on its short-term performance.
Investors considering Berkeley Group Holdings should weigh the company’s robust operational history and brand strength against current market challenges and valuation concerns. As always, a balanced approach, considering both macroeconomic trends and company-specific factors, will be crucial in making an informed investment decision.