Antofagasta PLC (LSE: ANTO.L), a prominent player in the copper mining sector, presents an intriguing opportunity for investors seeking exposure to the basic materials industry. With a market capitalization of $33.52 billion, Antofagasta is a significant entity within the United Kingdom, operating on a global scale with a presence in various countries including Chile, the United States, and key Asian markets.
Currently trading at 3400 GBp, Antofagasta’s stock has experienced a modest price change, showing a slight decrease of 0.01%. Despite this minimal movement, the company’s 52-week range between 2,577.00 and 4,455.00 GBp indicates substantial volatility, offering potential for both risks and rewards depending on market conditions and investor sentiment.
A standout feature of Antofagasta’s financial profile is its robust revenue growth of 17.90%, underscoring the company’s capability to enhance its top-line performance amidst fluctuating commodity prices. Moreover, the firm’s return on equity at 17.85% demonstrates effective management of shareholders’ funds, potentially appealing to investors looking for well-managed companies with efficient capital allocation.
From a valuation perspective, Antofagasta exhibits a forward P/E ratio considerably high at 1,688.74, which might raise eyebrows among value-focused investors. This figure suggests expectations of significant earnings growth or reflects the market’s confidence in the company’s future profitability, although it also highlights the need for careful scrutiny of future earnings projections.
Antofagasta’s dividend yield of 1.72% and a payout ratio of 38.21% suggest a balanced approach to rewarding shareholders while retaining sufficient capital for reinvestment. This aspect may appeal to income-seeking investors who value consistent dividend payments alongside potential capital appreciation.
The analyst ratings present a mixed sentiment with 7 buy ratings, 10 hold ratings, and 5 sell ratings. The average target price of 3,851.88 GBp suggests a potential upside of 13.29%, indicating optimism among analysts about the stock’s future performance. However, the wide target price range from 2,476.01 to 4,971.88 GBp reflects varied expectations about the company’s capability to navigate the challenges and opportunities within the copper market.
Technical indicators provide a nuanced picture. The 50-day moving average at 3,779.08 GBp and the 200-day moving average at 3,767.23 GBp indicate that the stock is trading below these levels, which might be a signal for potential bullish momentum if the stock price can surpass these averages. Meanwhile, the RSI (Relative Strength Index) of 52.18 suggests that the stock is neither overbought nor oversold, offering a neutral outlook in terms of momentum.
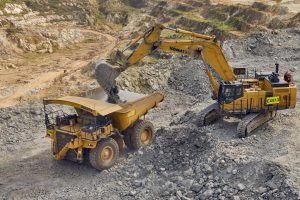
Antofagasta’s operations span across mining, exploration, and transportation, with copper being the primary commodity. The company’s strategic focus on copper, a critical component in renewable energy technologies and electric vehicles, positions it advantageously in the context of global green energy transitions.
For investors considering Antofagasta, the potential for a 13.29% upside, alongside its strong revenue growth and strategic operations in the copper sector, presents a compelling case. However, the elevated forward P/E ratio and market volatility necessitate a cautious approach, emphasizing the importance of aligning investment decisions with individual risk tolerance and market outlook.