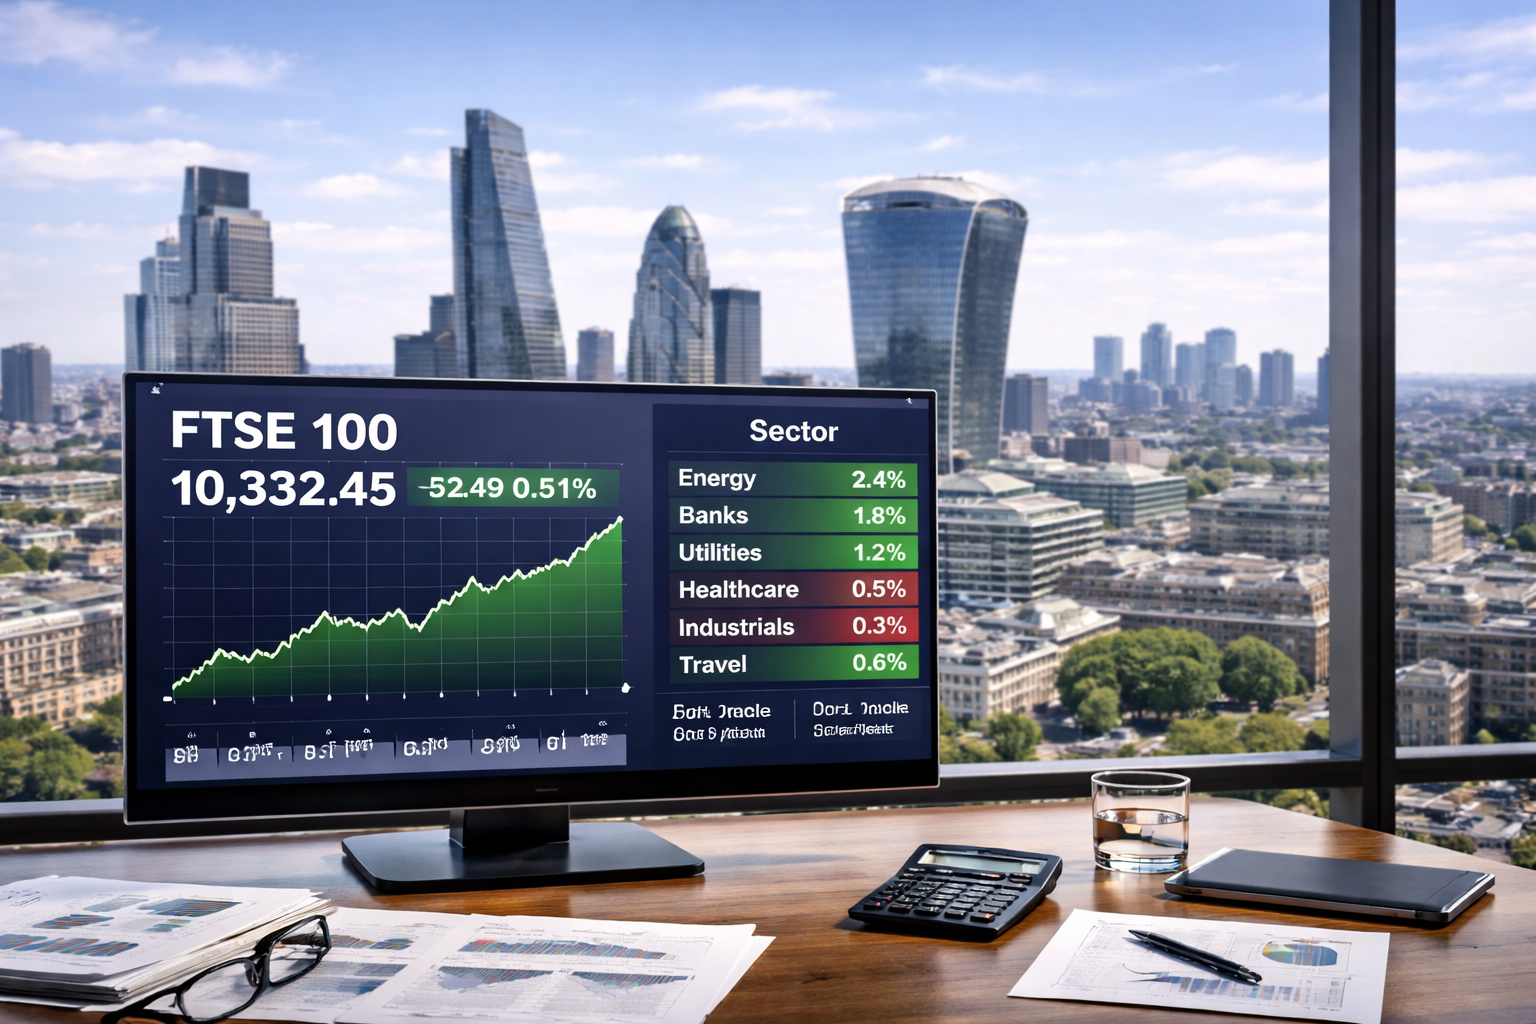
The FTSE 100 traded higher in midday London trading on Tuesday as strength in energy and banking stocks lifted the index. The benchmark was moving around the 10,300–10,350 range, showing a modest gain as investors responded to firm oil prices and a more positive tone across parts of the European market.
Market sentiment remained influenced by developments in global energy markets, with elevated oil prices continuing to support resource-heavy indices such as the FTSE 100.
Energy and Banking Stocks Drive the Advance
Energy companies were among the strongest performers during the session as higher crude prices supported earnings expectations for major oil producers. Given the FTSE 100’s weighting towards oil and gas companies, movements in energy markets continue to play a significant role in shaping index performance.
Banking stocks also moved higher, contributing to the upward momentum. Financials benefited from a stabilisation in market sentiment following recent volatility, with investors rotating back into economically sensitive sectors.
Sector Winners
Several sectors showed strength during the session, led by energy, financials and utilities.
Companies benefiting from these trends included major oil producers and large banking groups, alongside some defensive names in utilities which also attracted steady demand.
Sector Losers
Despite the broader gains, some sectors remained under pressure.
Travel and leisure stocks traded more cautiously as higher fuel costs continue to weigh on airline margins. Mining stocks also showed mixed performance, reflecting ongoing uncertainty in metals markets and global demand expectations.
Currency and Macro Context
Sterling traded relatively steady against the US dollar during the session. Currency stability provided a neutral backdrop for multinational companies listed on the FTSE 100, many of which generate a large proportion of revenues overseas.
The GBP to EUR exchange rate remains a key indicator of relative economic strength between the UK and the eurozone. Movements are typically driven by differences in interest rate expectations between the Bank of England and the European Central Bank, inflation trends, and overall economic growth outlooks. In the current environment, sterling has been relatively stable against the euro, supported by expectations around UK monetary policy, although energy prices, geopolitical developments and broader risk sentiment continue to influence short-term fluctuations. A weaker pound tends to benefit UK-listed multinationals by increasing the value of overseas earnings, while a stronger pound can reduce that effect but improve import costs.
Investor attention remains focused on upcoming central bank decisions, particularly from the Bank of England, as markets assess the outlook for interest rates in the context of elevated energy prices and inflation concerns.
Market Outlook
The FTSE 100’s ability to move higher despite ongoing geopolitical tensions highlights continued support from energy and financial sectors. Commodity prices, monetary policy expectations and global risk sentiment are likely to remain key drivers of market direction in the near term.