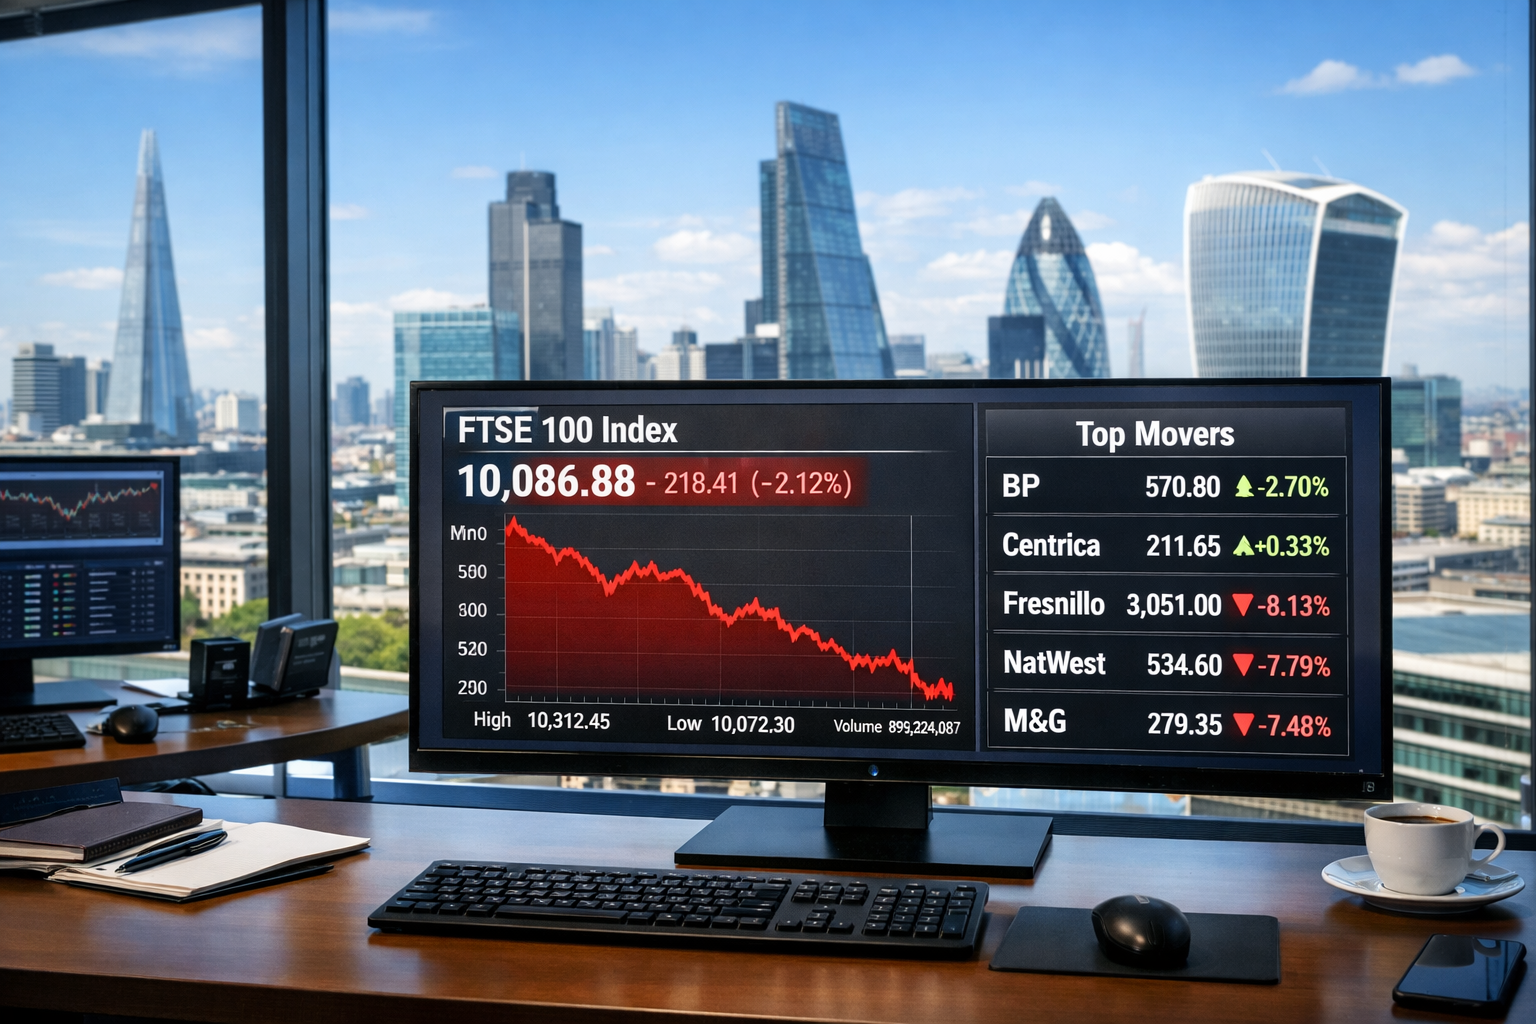
The FTSE 100 fell notably in midday London trading on Wednesday, with the index at 10,086.88, down 218.41 points (2.12%), as widespread selling across financial and mining stocks weighed heavily on the benchmark.
The decline reflects a broad-based move lower across UK equities, with risk sentiment weakening as investors reduce exposure to cyclical and commodity-linked sectors.
Energy Stocks Provide Limited Support
Energy stocks were among the few areas of strength during the session. BP led the risers, supported by firmer oil prices, while Centrica also traded slightly higher.
Defensive consumer names such as Imperial Brands showed marginal gains, although the overall strength in these sectors was limited.
Top Risers
- BP. – BP Plc up 2.70% to 570.80p
- CNA – Centrica plc up 0.33% to 211.65p
- IMB – Imperial Brands Group up 0.06% to 3,129.00p
These gains were not sufficient to offset broader market weakness.
Financial and Mining Stocks Lead the Sell-Off
Selling pressure was concentrated in financials and mining stocks, which were among the worst performers during the session.
Fresnillo recorded the steepest decline, reflecting weakness in precious metals sentiment. Banking group NatWest and asset manager M&G also fell sharply, highlighting pressure across the financial sector.
Mining company Endeavour Mining added to the downside, underlining weakness across resource stocks.
Top Fallers
- FRES – Fresnillo plc down 8.13% to 3,051.00p
- NWG – NatWest Group plc down 7.79% to 534.60p
- MNG – M&G plc down 7.48% to 279.35p
- EDV – Endeavour Mining plc down 7.22% to 4,086.00p
The scale of these declines reflects a broad risk-off move across key sectors of the index.
Currency and Macro Context
Sterling traded relatively steady against both the euro and US dollar, suggesting currency movements were not the primary driver of today’s decline.
Instead, the sell-off appears linked to broader market sentiment, with investors reacting to global economic uncertainty, commodity price volatility and evolving expectations around interest rates.
Pound and Euro
The pound and the euro continue to trade within a relatively narrow range, as investors weigh weak growth signals against persistent inflation risks across both economies.
In the United Kingdom, recent data point to a loss of momentum. Monthly GDP figures show the economy stagnating at the start of the year, reinforcing the view that growth remains fragile. While the services sector continues to support activity, broader economic expansion has been limited.
Inflation remains above the Bank of England’s target, with the latest reading near 3%. Although policymakers expect inflation to ease in the coming months, recent increases in global energy prices introduce uncertainty into that outlook. Higher oil and gas costs could feed through to consumer prices later in the year.
The Bank of England has maintained a cautious stance, with internal divisions over the timing of future rate cuts. Some policymakers are increasingly focused on weak growth, while others remain concerned about underlying inflation pressures.
In the eurozone, inflation is closer to target, with recent estimates indicating a rate just below 2%. This has allowed the European Central Bank to adopt a more stable policy stance, although officials continue to emphasise the need for further data before making any policy adjustments.
Growth conditions in the euro area remain mixed. Industrial production has shown weakness, particularly in manufacturing, but business surveys suggest the wider economy continues to expand at a modest pace.
Purchasing Managers’ Index data highlight a divergence between the two regions. The UK continues to record stronger activity readings, driven largely by services, while the eurozone shows slower but still positive growth.
Energy markets remain a key factor for both currencies. Oil prices are holding near recent highs, and European gas prices have risen in recent weeks. These developments increase the risk of renewed inflation pressure and may influence central bank decisions in the months ahead.
Market Outlook
With the FTSE 100 falling towards the 10,000 level, the market is showing increased sensitivity to macroeconomic developments. The sharp decline highlights a shift towards risk reduction, particularly in financial and mining sectors, while selective strength in energy stocks provides limited support.