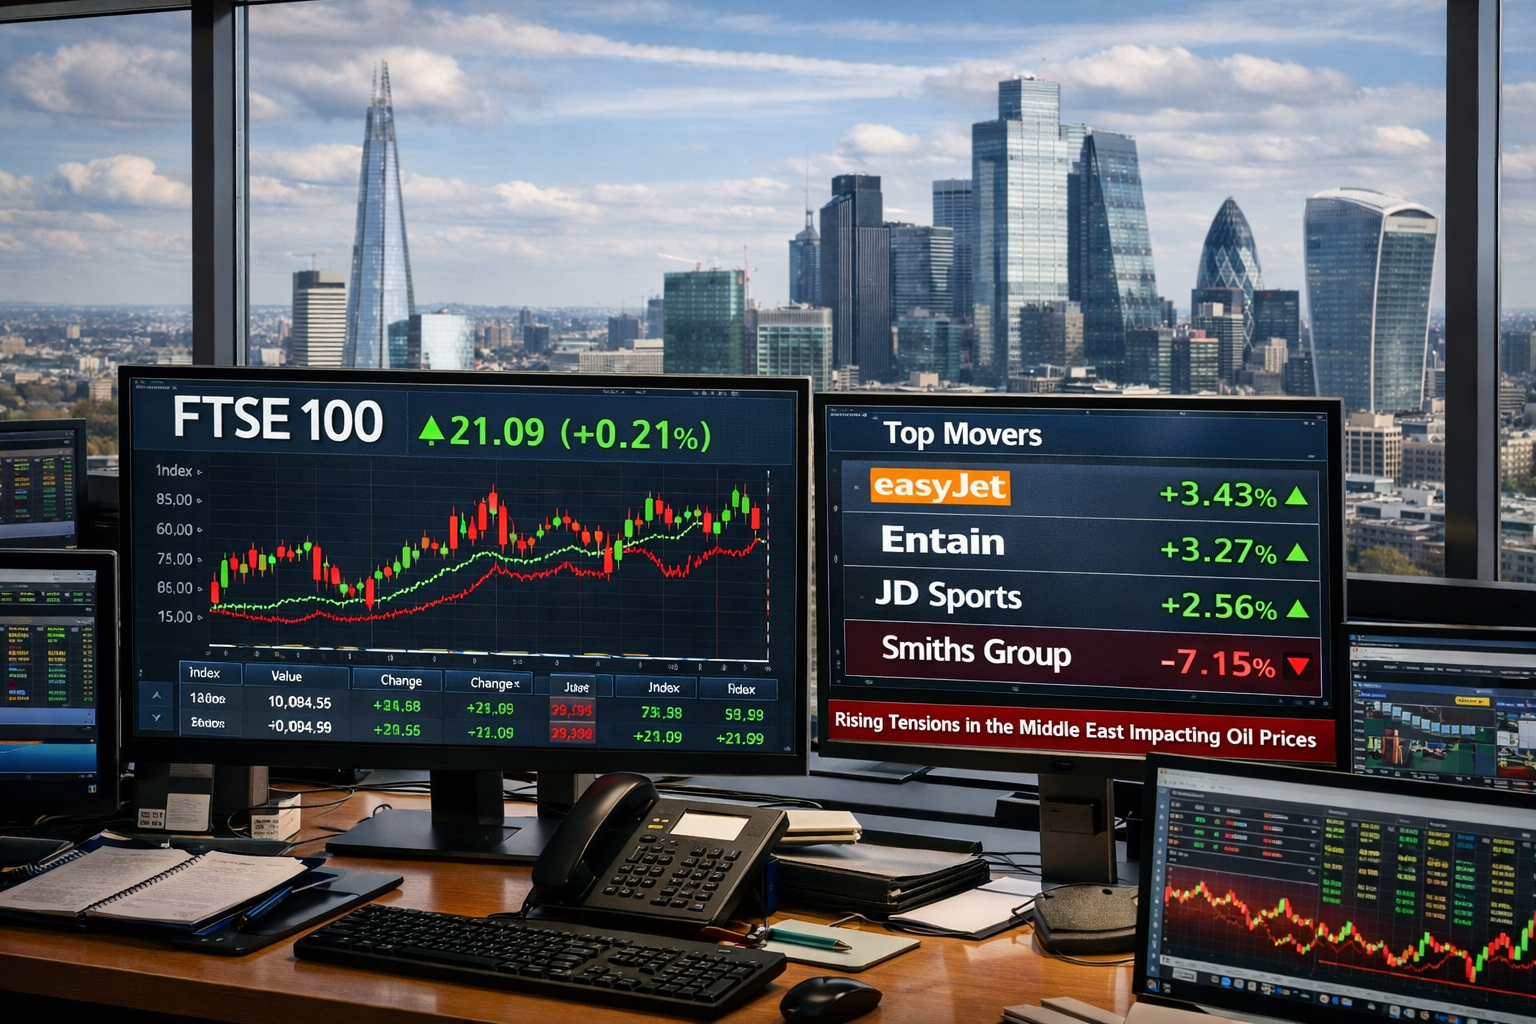
The FTSE 100 traded modestly higher in midday London trading on Friday, rising 21.09 points to 10,084.59, a gain of 0.21%, as gains in travel, leisure and consumer-facing stocks helped offset continued weakness in energy and industrial names. Despite the intraday rise, the index remains under pressure when viewed against the backdrop of the ongoing Iran conflict, which has driven volatility across global markets since late February.
Travel and consumer stocks lead gains
Gains across the index were led by Metlen Energy & Metals, which rose 3.79%, while easyJet added 3.43% as airline stocks recovered after recent disruption linked to Middle East airspace and energy price volatility. Entain climbed 3.27%, with Pershing Square Holdings also higher by 2.78%.
Retail and industrial names contributed to the upside, with JD Sports Fashion gaining 2.56% and Melrose Industries advancing 2.10%. The strength in these sectors reflects selective buying following recent market weakness, particularly in areas less directly exposed to rising energy costs.
Smiths Group leads fallers as energy stocks decline
On the downside, Smiths Group fell sharply by 7.15%, leading the FTSE 100 fallers. The move reflects continued pressure on industrial and engineering stocks, which are sensitive to rising input costs and economic uncertainty.
Energy majors also weighed on the index, with BP down 3.14% and Shell slipping 1.11%. While oil prices remain elevated, volatility in energy markets has created uneven performance across the sector. ICG, Babcock International and BAE Systems also posted modest losses, reflecting a mixed but cautious tone across the index.
Market remains under pressure since Iran conflict escalation
While today’s session shows a modest gain, the FTSE 100 remains below levels seen prior to the escalation of the Iran conflict at the end of February. The outbreak of hostilities triggered a sharp and immediate reaction across global markets, as energy prices surged and investors moved towards safer assets.
In the days following the escalation, the FTSE 100 experienced a broad sell-off, with the index falling sharply as oil prices climbed above $100 per barrel and supply concerns intensified. The disruption to shipping through key routes such as the Strait of Hormuz, which carries a significant share of global oil and gas flows, has been a central driver of market volatility.
Higher energy prices have fed directly into inflation expectations, raising concerns that central banks, including the Bank of England, may need to maintain higher interest rates for longer. This shift in expectations has weighed on equities, particularly in sectors sensitive to borrowing costs and consumer demand.
Although the FTSE 100 has shown resilience at times, supported in part by its exposure to global energy producers, the overall trend since the start of the conflict has been one of increased volatility and downward pressure.
Oil price volatility and inflation concerns shape sentiment
Energy markets have remained highly volatile, with oil and gas prices rising sharply following attacks on key infrastructure in the Middle East. These developments have reinforced concerns about supply disruptions and the potential for sustained higher energy costs.
For the UK economy, this has significant implications. Higher energy prices feed through into household bills and business costs, increasing inflationary pressure at a time when price growth remains above target. This dynamic has shifted expectations around monetary policy, with markets now anticipating the possibility of further interest rate increases rather than cuts.
Rising borrowing costs are already being reflected in higher gilt yields and mortgage rates, adding another layer of pressure on consumers and businesses. This combination of factors has contributed to a cautious market environment, with investors weighing the risk of slower economic growth against persistent inflation.
Sterling under pressure against the dollar and euro
Currency markets have also reflected the impact of the geopolitical backdrop. The pound has come under pressure against the US dollar, which has strengthened as investors seek safety amid global uncertainty. A stronger dollar is a typical feature during periods of geopolitical stress, and this has weighed on sterling in recent weeks.
Against the euro, the pound has been more stable with slight gains, but still faces pressure from the UK’s exposure to rising energy costs and inflation risks. The euro has shown relative resilience, supported by expectations around European Central Bank policy and differing economic dynamics within the eurozone.
For UK investors, currency movements add another dimension to market performance. A weaker pound can support multinational earnings within the FTSE 100, given the index’s global exposure, but it also reflects underlying economic concerns and contributes to imported inflation.
A balanced but cautious session
Today’s modest rise in the FTSE 100 highlights a balanced market, where gains in travel, leisure and consumer stocks are being offset by weakness in energy and industrial names. The overall move remains limited, suggesting investors are maintaining a cautious stance.
While the index has avoided further sharp declines in this session, the broader trend since the escalation of the Iran conflict remains one of uncertainty and sensitivity to external developments. Markets continue to react to shifts in energy prices, geopolitical headlines and central bank expectations.
The FTSE 100’s slight rise today reflects short-term stability rather than a change in direction. The impact of the Iran conflict continues to influence markets through energy prices, inflation expectations and currency movements. Until there is greater clarity on geopolitical developments and the outlook for interest rates, the index is likely to remain volatile, with sentiment driven more by external factors than company-specific news.